[Analysis] What is a Mutual Fund – How It Works | Structure and Regulation | Types, Costs and Taxation
- Blog|Company Law|
- 7 Min Read
What a mutual fund is, how it works, its types, structure, costs, returns and taxation—the complete guide, built from the official NISM syllabus.
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

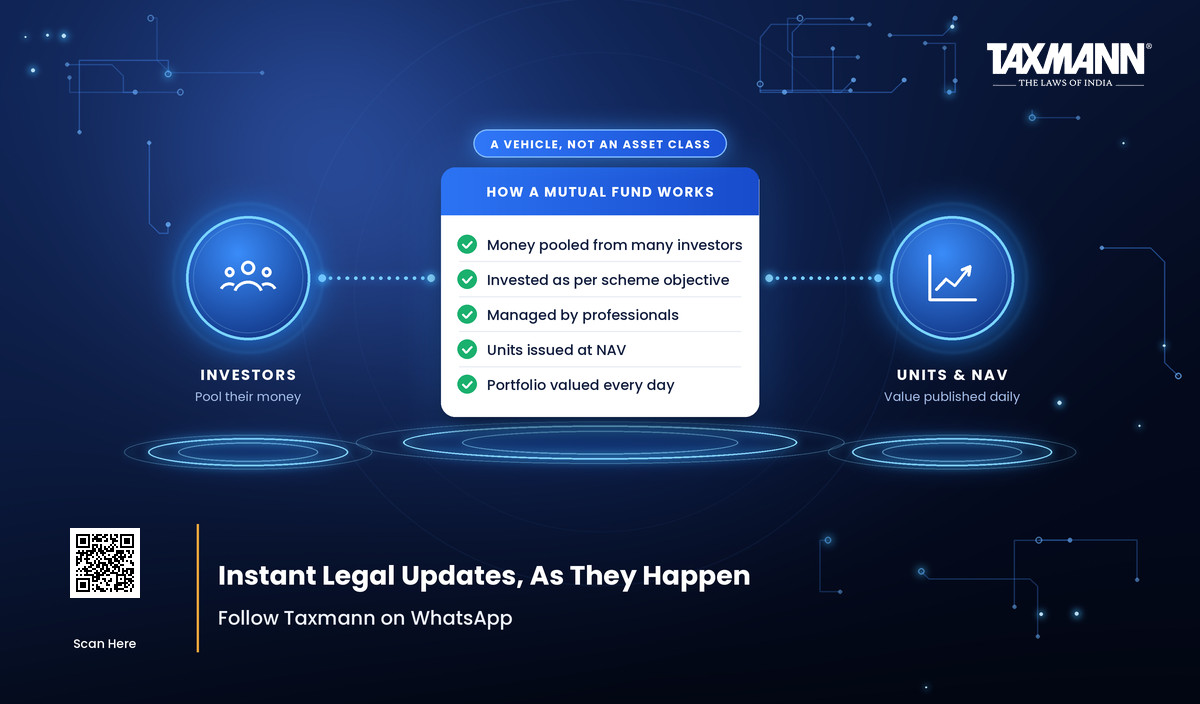
Table of Contents
- The distinction almost everyone gets wrong
- First, a step back: saving vs investing
- How a mutual fund actually works
- Why investors use mutual funds
- And why they don’t suit everyone
- The types of mutual funds
- Who runs it—and who protects you
- What it costs you
- How your returns are measured
- How you’re taxed
- Investing, practically
- Want to sell mutual funds, not just buy them?
- Quick answers
1. The distinction almost everyone gets wrong
Here is a precision point that professionals are expected to know, and most investors have never heard.
You do not invest in a mutual fund. You invest through one.
We all say “I’ve invested in a mutual fund”, and for everyday conversation that’s fine. But technically it is not correct—and the difference is not pedantry. When someone says they invested in a mutual fund scheme, the scheme gets mentally filed alongside equity shares, debentures and bonds, as though it were a competing instrument.
It isn’t. A mutual fund is not an asset class. It is the vehicle through which you invest in those instruments. The scheme buys the shares and bonds; you own units of the scheme. Get this right and a great deal of the rest of the subject falls into place.
2. First, a step back: saving vs investing
Before mutual funds, the basics. Saving and investing are not the same thing—but nor are they opposites. They are two steps of one process.
- Saving shares a root with “safe”. Its priority is the safety of your money, and it means reducing consumption so that money is left over.
- Investing takes that saved money and seeks profit—accepting a trade-off between risk and return.
Saving therefore precedes investing. You cannot invest what you have not first saved.
How to evaluate any investment product
Whatever the product, the same framework applies:
| Factor | The question it answers |
|---|---|
| Safety | Is my capital—and my income—secure? |
| Liquidity | Can I convert this to cash at fair value, easily? Can I sell part of it? |
| Returns | What do I earn—as current income, or capital appreciation? |
| Convenience | How easy is it to invest, exit, check value, receive income? |
| Ticket size | What is the minimum I need to start? |
| Taxability | What do I keep after tax? |
| Tax deduction | Is a deduction available—and at what cost in lock-in? |
Never read any one factor in isolation. A product with attractive tax treatment may be unsafe; a product offering a deduction may lock your money away. Every attractive feature is usually paid for somewhere else in the table.
The four asset classes
| Asset class | Type |
|---|---|
| Real estate | Real asset |
| Commodities (notably gold and silver) | Real asset |
| Fixed income | Financial asset |
| Equity | Financial asset |
Real assets exist physically; financial assets exist only in financial form. Real estate is illiquid and indivisible, and carries high transaction and maintenance costs that most investors forget to subtract. Gold and silver are globally accepted stores of value.
Mutual funds are how most people access the two financial asset classes—and, through gold and silver ETFs, the commodity ones too.
3. How a mutual fund actually works
Units. You get units in exchange for your money. Units × face value (commonly ₹10) is the scheme’s unit capital.
NAV. The Net Asset Value is the per-unit value of the scheme—the net realisable value per unit, i.e. how much could be generated per unit if the scheme’s holdings were sold. It’s the reference price for every purchase and redemption.
Read more: NAV in Mutual Funds
AUM. Assets Under Management is the total value the scheme manages—also obtainable as current NAV × units outstanding. It’s the standard measure of a fund house’s size.
Read more: AUM in Mutual Funds
Mark-to-market. Because NAV is published daily, every security in the portfolio is valued at current market price every day. That process—mark-to-market—produces the daily NAV, and the daily movement in it.
4. Why investors use mutual funds
| Advantage | What it means in practice |
|---|---|
| Professional management | Investing per a stated objective, on research, through prudent processes—including administrative work like collecting interest, dividends, rights and buybacks |
| Affordable diversification | Proportionate ownership of a diversified portfolio for as little as ~₹500—so all your eggs aren’t in one basket |
| Economies of scale | A distinct cost advantage versus investing directly |
| Liquidity | You can realise your investment’s value from the fund itself—subject to the scheme’s structure |
| Transparency | Scheme documents (SID, SAI, KIM), portfolio disclosures and daily NAV—available even to prospective investors |
| Tax deferral | The scheme’s income is exempt, so gains compound untaxed until you redeem |
| Tax benefits | ELSS offers a deduction under section 123 of the Income-tax Act, 2025 (old section 80C), in the old regime only |
| Convenient options | Structure your investment to suit liquidity and tax position |
| Investment comfort | Further purchases need very little documentation |
| Regulatory comfort | SEBI mandates strict checks and balances |
| Systematic approach | SIP, SWP and STP promote discipline |
A useful test of the diversification claim: investing directly in the securities markets would require you to open and manage a broking account, a demat account and other relationships. A mutual fund collapses all of that into one transaction.
5. And why they don’t suit everyone
Good content admits the other side. The NISM workbook is candid about four limitations:
| Limitation | The reality |
|---|---|
| No portfolio customisation | You’re one of thousands of unit-holders. You cannot influence what the scheme buys. (A PMS offers this—for large investors.) |
| Choice overload | Many fund houses, many schemes, many options. SEBI’s categorisation exists partly to tame this. |
| No control over costs | Costs are shared in proportion to holdings. You cannot control them—though SEBI caps them, and market forces push many schemes below the cap. |
| No guaranteed returns | A mutual fund is a pass-through vehicle. It passes risk and return to you. Returns depend on the market, the securities held and the manager’s skill—and only the last of those is even partly controllable. |
6. The types of mutual funds
Three classifications, plus SEBI’s framework on top:
- By structure—open-ended, close-ended, interval (plus ETFs)
- By management—active vs passive
- By investment universe—equity, debt, money market, gold, international…
SEBI’s categorisation sorts every scheme into five broad groups: Equity (13 sub-categories), Debt (17), Hybrid (7), Life Cycle Funds, and Other Schemes (2)—with prescribed market-cap definitions and the multi-cap 25/25/25 rule.
Read more: Types of Mutual Funds
7. Who runs it—and who protects you
A mutual fund in India is a trust, governed by the Indian Trusts Act, 1882, with a deliberate three-tier structure:
Sponsor → Trustee → AMC
- The sponsor creates the trust and applies to SEBI.
- The trustees hold it and are legally charged with protecting the unit-holders, who are the trust’s beneficiaries.
- The AMC runs the schemes day to day—but the assets sit with a Custodian appointed by the trustees.
The manager, the custodian and the protector are three different parties. That separation is the investor protection.
Read more: AMC and Mutual Fund Structure
Regulation: SEBI regulates mutual funds in India. AMFI is not a regulator and not an SRO—it is the industry association, which registers distributors and can cancel an ARN for Code of Conduct breaches. And note: SEBI vets scheme documents; it does not approve them.
Read more: Who Regulates Mutual Funds in India
8. What it costs you
The Total Expense Ratio (TER) is charged to the scheme and is already inside the NAV. It’s why Direct and Regular plans of the same scheme have different NAVs—the Direct plan carries no distribution expenses or commission.
Read more: Expense Ratio (TER) in Mutual Funds
On exit, an exit load may apply, reducing what you receive below the stated NAV. Entry load is not permitted.
Read more: Exit Load in Mutual Funds
9. How your returns are measured
Four measures, four different questions: simple return, annualised return, compounded return (CAGR) and total return. For risk-adjusted performance there are two: the Sharpe Ratio and the Information Ratio—the latter being the only risk-adjusted measure AMCs must disclose, daily, against the scheme’s tier-1 benchmark.
Read more: How Mutual Fund Returns Are Calculated · Sharpe Ratio and Information Ratio
10. How you’re taxed
Two levels. The scheme’s income is exempt (section 10(23D) of the 1961 Act, continued under the Income-tax Act, 2025). You are taxed on capital gains when you redeem, and on IDCW at your slab rate. Holding periods are 12 months (listed securities and equity-oriented funds) or 24 months (other assets), with grandfathering to 31 January 2018 for equity funds.
Read more: Mutual Fund Taxation in India · IDCW in Mutual Funds · ELSS and Section 123 (Old Section 80C)
11. Investing, practically
Getting in: a scheme launches through an NFO, then re-opens at NAV-based prices.
Read more: NFO in Mutual Funds
Getting compliant: every investor must be KYC compliant, irrespective of the amount.
Read more: KYC for Mutual Fund Investors
Staying systematic: SIP to invest regularly, SWP to withdraw regularly, STP to move between schemes.
Read more: SIP, SWP and STP
12. Want to sell mutual funds, not just buy them?
Distributing mutual funds is a regulated profession with a defined entry route: NISM certification → KYD → ARN → empanelment with AMCs. Distributors are paid trail commission only, calculated on net assets and payable for as long as the client stays invested.
SEBI also created a simpler ‘new cadre’ route—for postal agents and retired government, teaching and banking professionals—with its own foundation-level certification, NISM-Series-V-B.
Read more: How to Become a Mutual Fund Distributor · NISM-Series-V-B Exam · ARN, EUIN and KYD
To learn it properly, start with the official NISM-Series-V-B Mutual Fund Foundation workbook, the material the certification exam is largely based on. The regulations themselves are on Taxmann.com | Research, and follow-up questions can go to Taxmann AI.
13. Quick answers
What is a mutual fund in simple words?
A professionally managed vehicle that pools money from many investors and invests it in securities. You hold units; the per-unit value is the NAV.
Do I invest in a mutual fund or through one?
Technically, through. A mutual fund is not an asset class—it’s the vehicle through which you hold shares, bonds and other securities.
How do mutual funds work?
You get units for your money. The scheme invests per its stated objective. The portfolio is valued daily (mark-to-market) to produce the NAV, at which you buy and redeem.
What is the minimum to start?
Diversification is available for as little as around ₹500—one of the format’s real advantages.
Are mutual fund returns guaranteed?
No. A mutual fund is a pass-through vehicle; it passes both risk and return to investors.
Who regulates mutual funds in India?
SEBI. AMFI is the industry association—not a regulator.
Is a mutual fund a company?
No—it is constituted as a trust under the Indian Trusts Act, 1882.
Law stated as on 16 November 2026. This article draws on Chapters 1, 2 and 3 of the official NISM-Series-V-B Mutual Fund Foundation workbook (March 2026 Workbook Version), published exclusively by Taxmann, read with the law in force on that date. It is general information, not investment, tax or legal advice.
More in this series: NAV in Mutual Funds · Types of Mutual Funds · AMC and Mutual Fund Structure · Mutual Fund Taxation in India · SIP, SWP and STP · How to Become a Mutual Fund Distributor
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


