[Analysis] Exit Load in Mutual Funds – Meaning | Worked Calculation | No Entry Load
- Blog|Company Law|
- 3 Min Read
Exit load is a charge on redemption that reduces what you actually receive. Here’s how it’s applied to NAV—with a worked example.
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

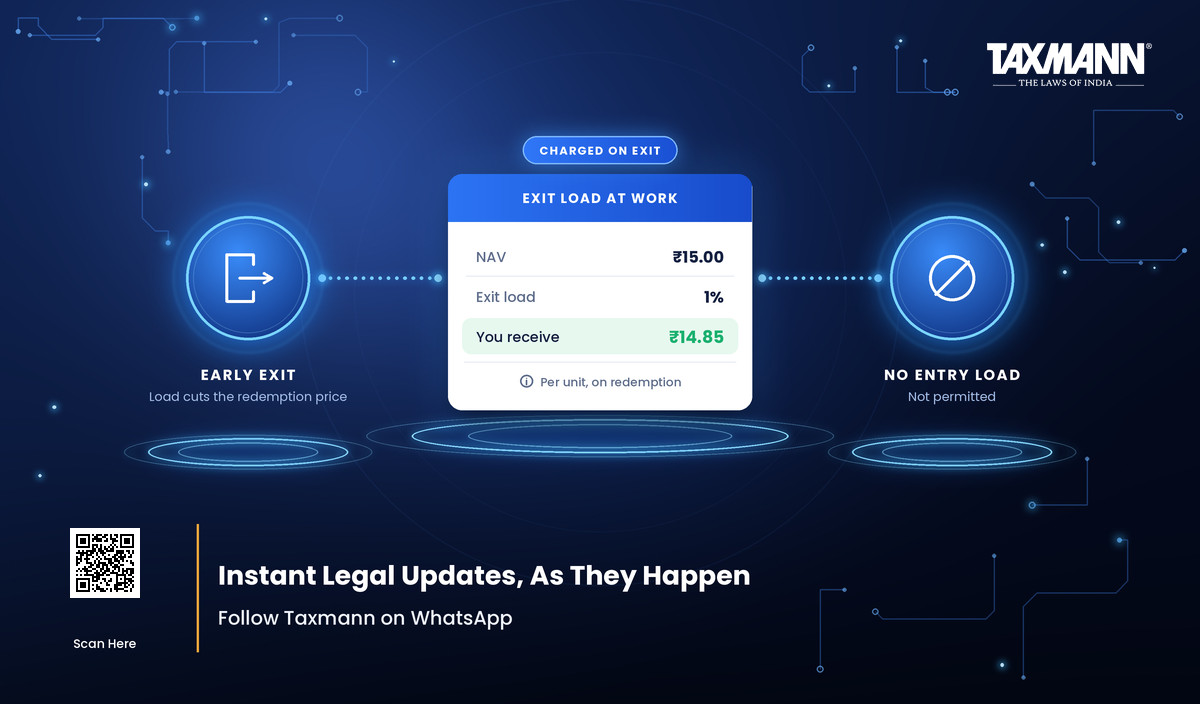
Table of Contents
- How is exit load calculated?
- Scheme return vs investor return
- Where else does your return leak?
- A note on promised returns
- Quick answers
1. How is exit load calculated?
The mechanic is simple: the investor receives the NAV minus the exit load.
Worked example. A scheme’s NAV is ₹15. An exit load of 1% applies. On redemption the investor receives 99% of ₹15—that is, ₹14.85 per unit.
That ₹0.15 gap is the whole point of the concept: it is the difference between the scheme’s return and the investor’s return.
2. Scheme return vs investor return
This distinction is worth internalising, because it is where most people misread performance.
| Based on | Reflects | |
|---|---|---|
| Scheme return | Closing NAV | How the fund performed |
| Investor return | NAV minus exit load (and after tax) | What you actually keep |
Loads drag the investor’s return below the scheme’s return. Tax pulls it down further. When computing investor returns for a period, use the amount actually received or receivable—NAV less exit load—not the headline NAV.
3. Where else does your return leak?
Loads are not the only drag. Taxes pull down post-tax returns further. So the sequence that matters to an investor is: scheme return → less exit load → less tax → what you actually keep. A scheme can post a perfectly good return while a short-held, loaded, taxed position delivers materially less.
The specific load applicable to a scheme, and the holding period over which it applies, are set out in that scheme’s Scheme Information Document (SID). Always read it there rather than assuming.
4. A note on promised returns
Mutual funds may not promise returns unless the scheme is an assured-returns scheme—which requires a named guarantor in the Scheme Information Document, who must actually pay if the scheme cannot meet the assured return. SEBI’s advertisement code governs how performance may be presented.
Chapter 7 of the Mutual Fund Foundation workbook works through loads and transaction pricing with formulae and illustrations.
5. Quick answers
Is entry load allowed in India?
No. Entry load is not permitted under current regulations.
How is exit load applied?
It is deducted from the applicable NAV, so you receive NAV less the load.
Does exit load reduce my returns?
Yes—it makes your investor return lower than the scheme’s return, and tax reduces it further.
Can a mutual fund promise me a return?
No—unless it is an assured-returns scheme, which requires a guarantor named in the SID who must pay if the scheme cannot meet the assured return.
Where do I find a scheme’s exit load?
In its Scheme Information Document (SID).
Which NAV a redemption gets depends on the cut-off time; see our note on mutual fund cut-off time and applicable NAV.
Law stated as on 16 November 2026. This article draws on Chapter 7 of the official NISM-Series-V-B Mutual Fund Foundation workbook (March 2026 Workbook Version), published exclusively by Taxmann, read with the law in force on that date. It is general information, not investment, tax or legal advice.
More in this series: What is a Mutual Fund · Expense Ratio (TER) in Mutual Funds · SIP, SWP and STP · How Mutual Fund Returns Are Calculated · NAV in Mutual Funds
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


