Residential status of an individual under section 6(2): the 182-day test, whether the arrival date counts, the employment relief and the Rs. 15 lakh rule.
Author: Taxmann
Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that's easy to read and remain consistent across all imprint and digital publications are applied
Section 115H is now section 217 of the Income-tax Act 2025. Which Act decides an NRI’s residence each year, sections 213 to 216, and the 115F claw-back.
Tax residency certificate under section 159(8): what it proves after Tiger Global (SC, 15 January 2026), and why Rule 75 now needs Form 41 in every claim.
RNOR status under section 6(13) and deemed residency under section 6(7): the three limbs, what RNOR is worth, the karta problem, withholding and the TRC.
Income-tax Act 2025 vs Income-tax Act 1961: which Act applies to which year, what moved to new sections, what changed and what section 536 keeps alive.
New Income-tax Rules 2026 for salaried employees: four new 50 per cent HRA cities, Form No. 124, higher allowance limits and revised perquisite values.
Section 393 of Income Tax Act 2025 replaces the 194-series with three TDS tables. See where 194C, 194J and 195 went, the new forms and TCS deadlines.
What a mutual fund is, how it works, its types, structure, costs, returns and taxation—the complete guide, built from the official NISM syllabus.
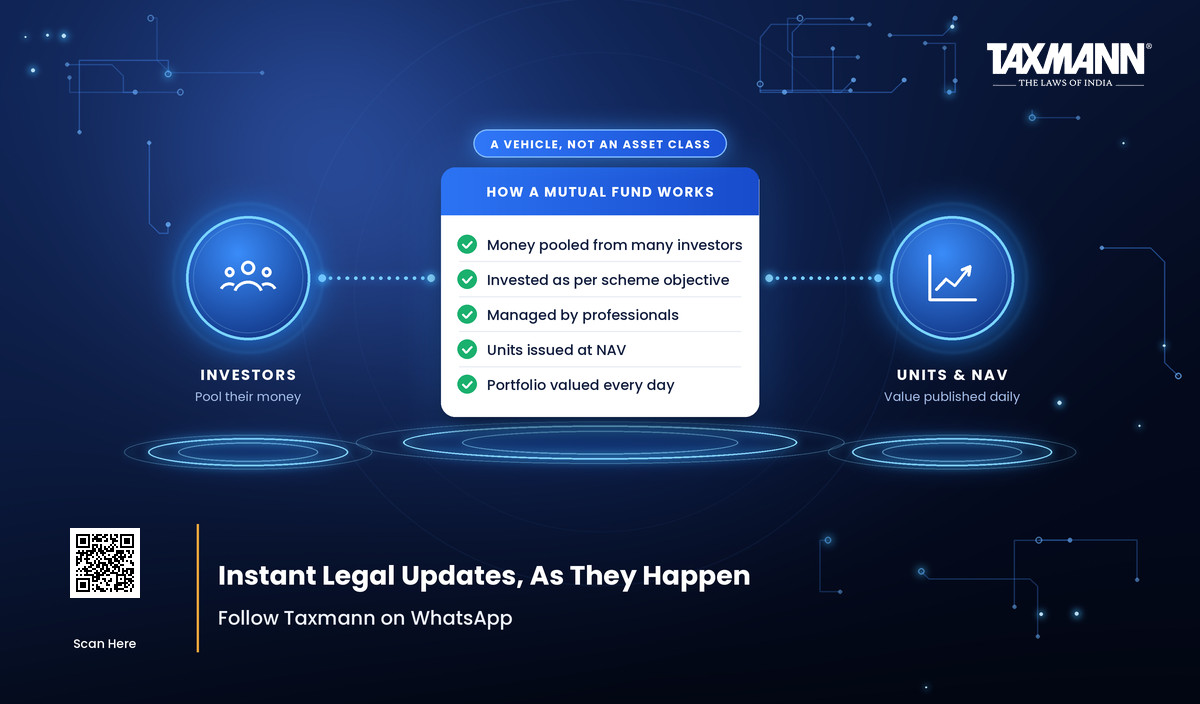
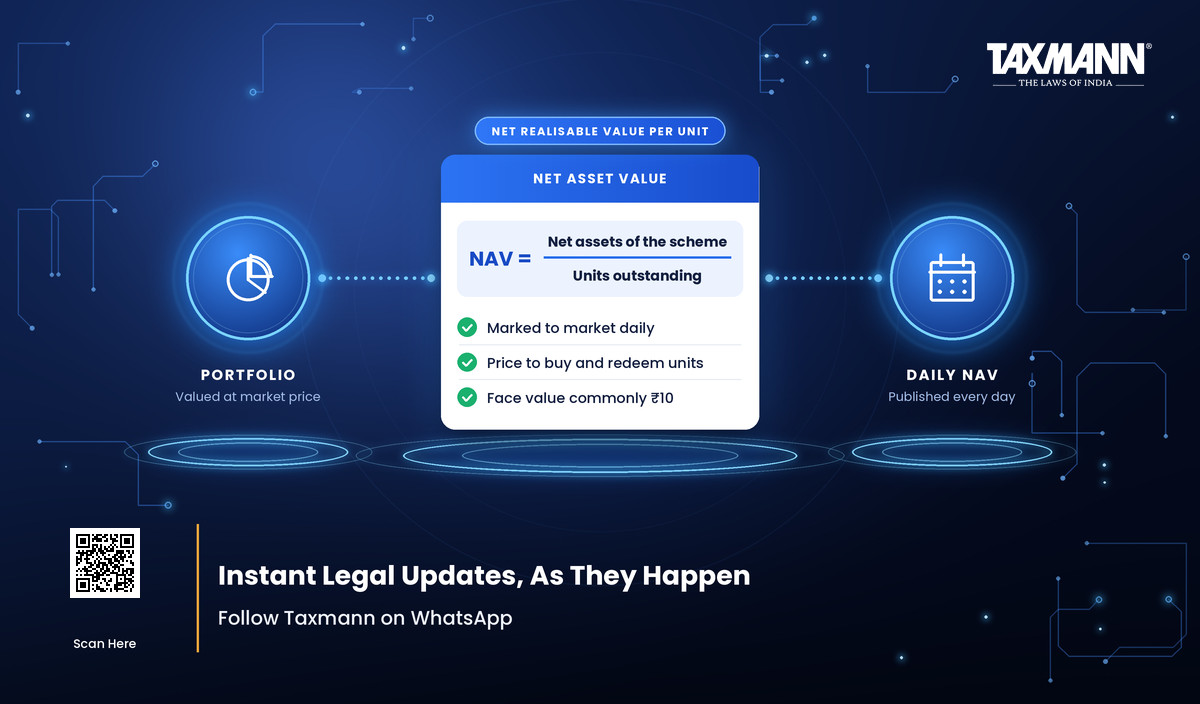
NAV is the per-unit value of a mutual fund scheme, calculated daily. Here’s how it’s arrived at, what moves it, and what it does *not* tell you.
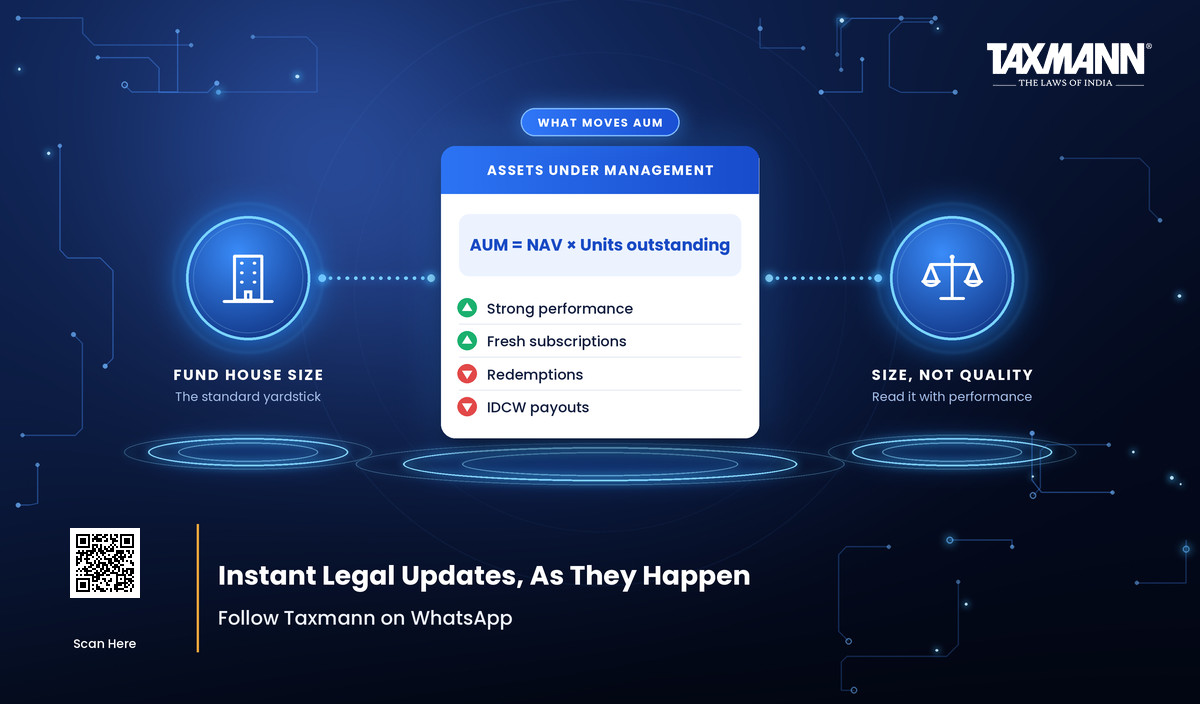
AUM is the total value a scheme manages. Here’s how it’s calculated, what moves it, and what it does and doesn’t tell you.









 CA | CS | CMA


