How deductions from gross total income work, the main Chapter VI-A deductions from 80C to 80U with their limits, which ones the new regime allows, where they sit in the Income-tax Act 2025, and how to claim them in the ITR.
Tag: Income-tax Act 2025

What exempt income is, how it differs from a deduction and a rebate, the common section 10 exemptions and their limits, where they sit in the Income-tax Act 2025, what the new regime allows, and how to report exempt income in the ITR.
What a superannuation fund is, approved vs unapproved funds, the Rs. 7.5 lakh limit on employer contributions, and how withdrawals are taxed under the Income-tax Act 1961 and the Income-tax Act 2025.
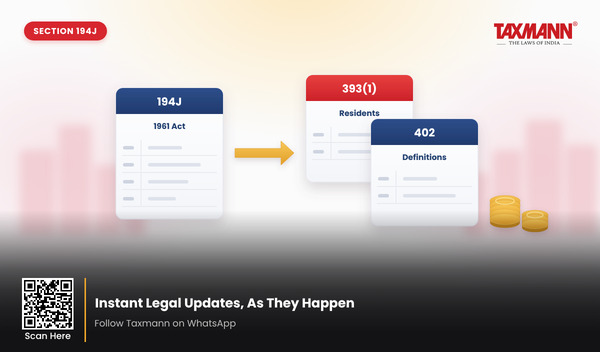
Section 194J now sits in section 393(1) of the Income-tax Act 2025, read with section 402. Where it sits, how to find the new section for any 1961 one, and how to cite rulings under the old number.
Section 115H is now section 217 of the Income-tax Act 2025. Which Act decides an NRI’s residence each year, sections 213 to 216, and the 115F claw-back.
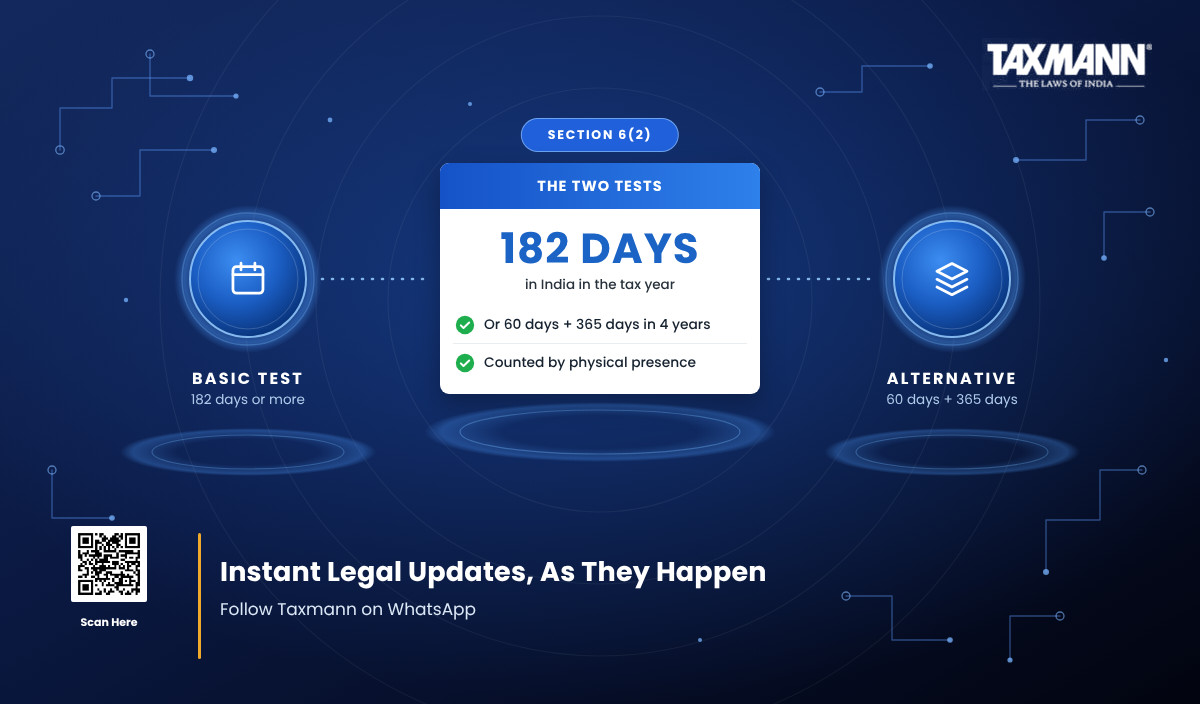
Residential status of an individual under section 6(2): the 182-day test, whether the arrival date counts, the employment relief and the Rs. 15 lakh rule.
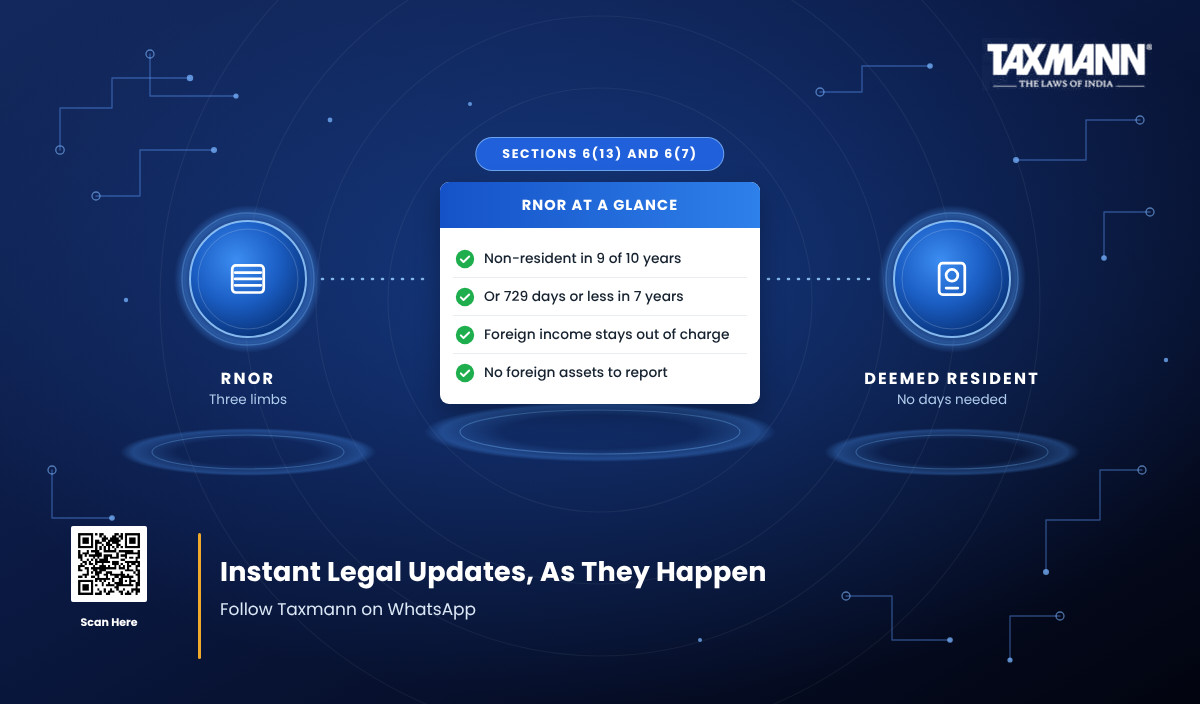
RNOR status under section 6(13) and deemed residency under section 6(7): the three limbs, what RNOR is worth, the karta problem, withholding and the TRC.
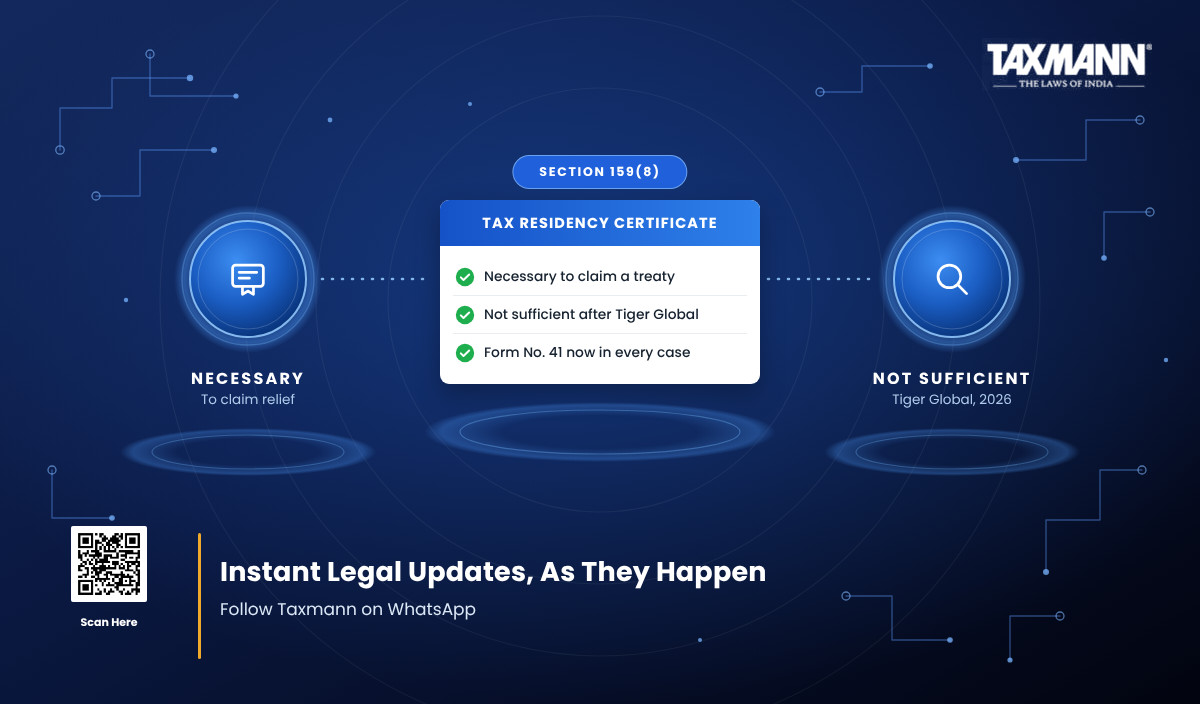
Tax residency certificate under section 159(8): what it proves after Tiger Global (SC, 15 January 2026), and why Rule 75 now needs Form 41 in every claim.
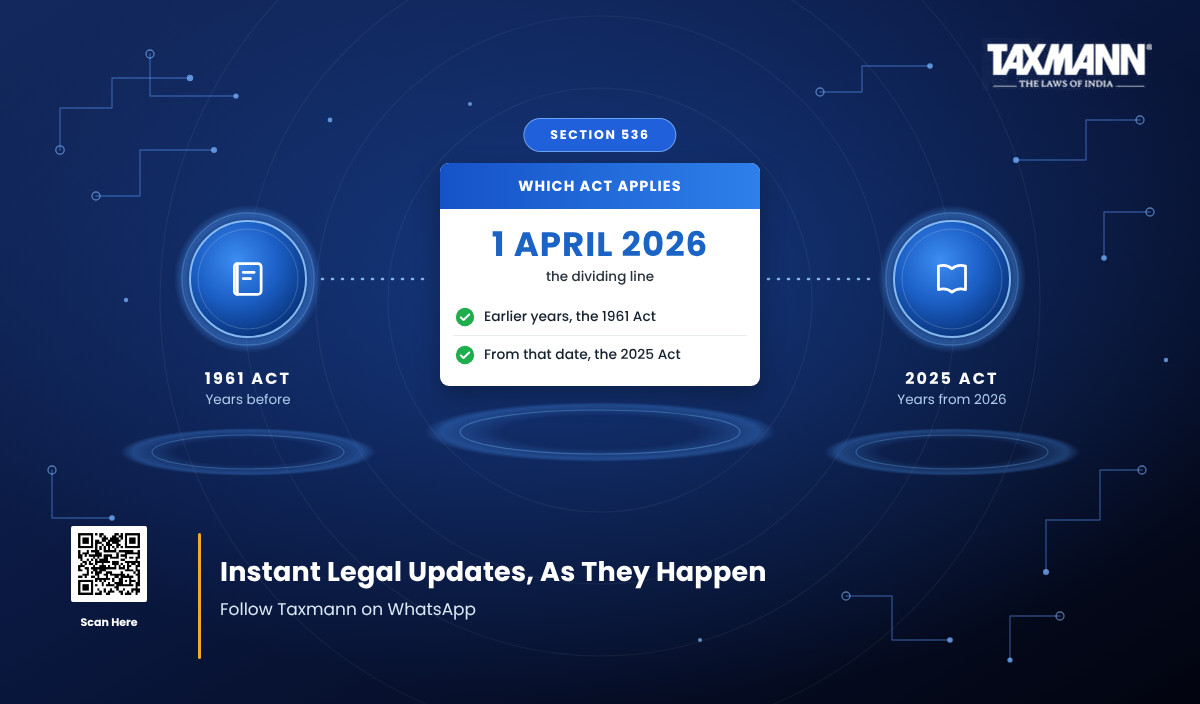
Income-tax Act 2025 vs Income-tax Act 1961: which Act applies to which year, what moved to new sections, what changed and what section 536 keeps alive.
New Income-tax Rules 2026 for salaried employees: four new 50 per cent HRA cities, Form No. 124, higher allowance limits and revised perquisite values.









 CA | CS | CMA


