[Analysis] How Mutual Fund Returns Are Calculated – Simple | Annualised | CAGR and Total Return
- Blog|Company Law|
- 3 Min Read
Four ways to measure a mutual fund return—and when each one misleads. With formulae and worked examples.
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

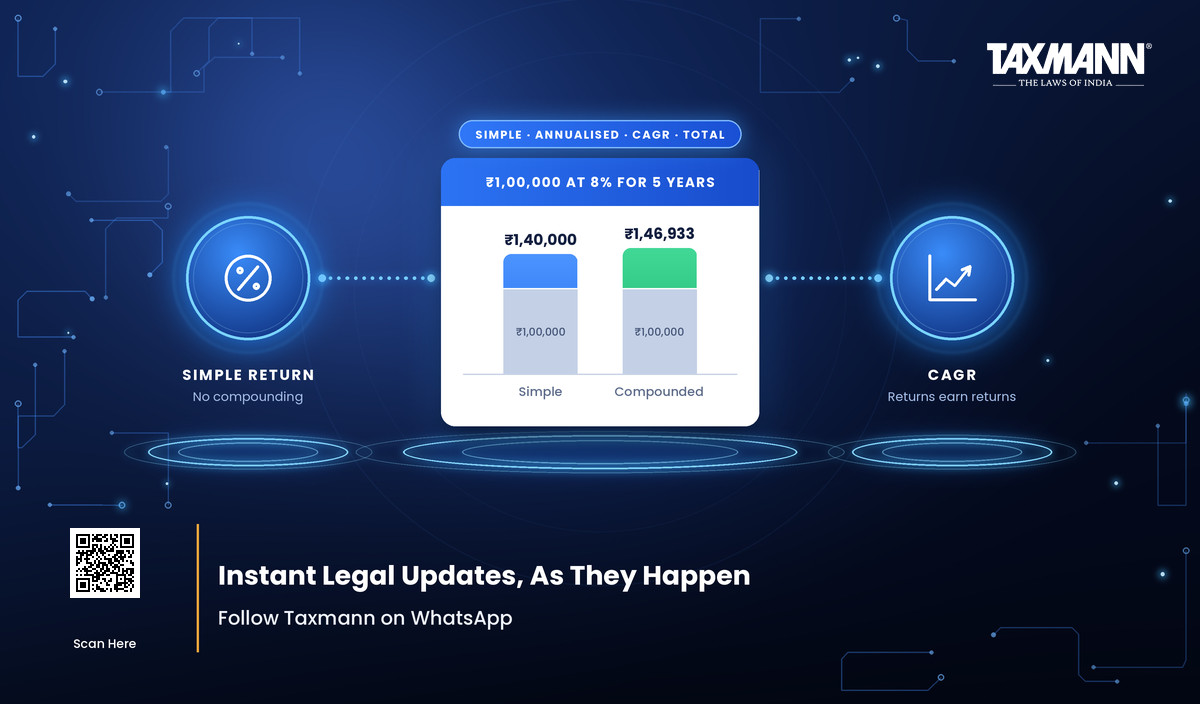
Table of Contents
- Simple return—what changed?
- Annualised return—comparing unequal periods
- Compounded return (CAGR)—for anything over a year
- Total return—don’t forget the payouts
- Which measure should you use?
- One more subtraction
- Quick answers
1. Simple return—what changed?
Simple return is just the change in value over a period.
Worked example. You invest at a NAV of ₹12. The NAV rises to ₹15. (15 − 12) ÷ 12 × 100 = 25%
Useful, but it says nothing about how long it took. Which is the whole problem.
2. Annualised return—comparing unequal periods
Two investments report returns since inception: one 5%, the other 3%. The first ran 6 months, the second 4 months. Those numbers are not comparable. Annualising fixes that.
| Investment | Simple return | Period | Annualised |
|---|---|---|---|
| Investment 1 | 5% | 6 months | 5 × 12 ÷ 6 = 10% |
| Investment 2 | 3% | 4 months | 3 × 12 ÷ 4 = 9% |
The ranking flips into view only after annualising. Investment 1 wins.
3. Compounded return (CAGR)—for anything over a year
For longer periods, simple annualisation overstates reality because it ignores compounding.
Why it matters—₹1,00,000 at 8% for 5 years:
| Year | Simple interest—value at year end | Compounding (CAGR)—value at year end |
|---|---|---|
| 1 | ₹1,08,000 | ₹1,08,000 |
| 2 | ₹1,16,000 | ₹1,16,640 |
| 3 | ₹1,24,000 | ₹1,25,971 |
| 4 | ₹1,32,000 | ₹1,36,049 |
| 5 | ₹1,40,000 | ₹1,46,933 |
Same rate, same money, same five years—a ₹6,933 gap. Under simple interest, the return is earned only on the original amount each year. Under compounding, each year’s return is added back to the principal, so interest earns interest. Over long horizons that gap widens dramatically.
4. Total return—don’t forget the payouts
A mutual fund can return money two ways: capital gains (or losses) and income distribution. Total return counts both.
Worked example. Ashish invests ₹1,00,000 at a NAV of ₹10 and is allotted 10,000 units. The scheme declares an IDCW of ₹2 per unit. The NAV is now ₹12.
- Begin value = ₹1,00,000
- End value = ₹12 × 10,000 = ₹1,20,000
- Distribution = ₹2 × 10,000 = ₹20,000
- Total return = [(1,20,000 − 1,00,000) + 20,000] ÷ 1,00,000 × 100 = 40%
But that 40% is not annualised. If it took five years, it is a very different proposition from one year. Where a payout has been made and compounding must be reflected, the CAGR technique prescribed by SEBI is used to compute total return.
5. Which measure should you use?
| Measure | Use it when | Its blind spot |
|---|---|---|
| Simple return | Period under a year, quick check | Ignores time entirely |
| Annualised return | Comparing different short periods | Ignores compounding |
| CAGR | Any period over a year | Hides the journey’s volatility |
| Total return | A scheme has paid out income | Not annualised on its own |
The rule of thumb: total return is the most comprehensive measure, but it is not appropriate on its own for periods longer than a year. Pair it with CAGR.
6. One more subtraction
Every figure above is a scheme return. Your investor return is lower—exit load and tax come off. See our guide to exit load for how that works.
The formulae and worked illustrations appear in full in Chapter 7 of the Mutual Fund Foundation workbook.
7. Quick answers
What is the full form of CAGR?
Compounded Annualised Growth Rate.
What is the CAGR formula?
(Later Value ÷ Initial Value)^(1/n) − 1, where n is the number of years.
Is CAGR better than simple return?
For any period over a year, yes—simple return ignores compounding and time.
Does total return include dividends?
Yes. It counts both capital gains/losses and income distributed.
Why does my actual return differ from the scheme’s return?
Exit load and tax reduce what you keep.
Law stated as on 16 November 2026. This article draws on Chapter 7 of the official NISM-Series-V-B Mutual Fund Foundation workbook (March 2026 Workbook Version), published exclusively by Taxmann, read with the law in force on that date. It is general information, not investment, tax or legal advice.
More in this series: What is a Mutual Fund · Sharpe Ratio and Information Ratio · NAV in Mutual Funds · Exit Load in Mutual Funds · SIP, SWP and STP
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


