[Analysis] Sharpe Ratio and Information Ratio – Formulas | Worked Example | Mandatory Disclosure
- Blog|Company Law|
- 3 Min Read
Return alone means nothing without the risk taken to get it. Here are the two risk-adjusted measures that matter—one of which AMCs must disclose.
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

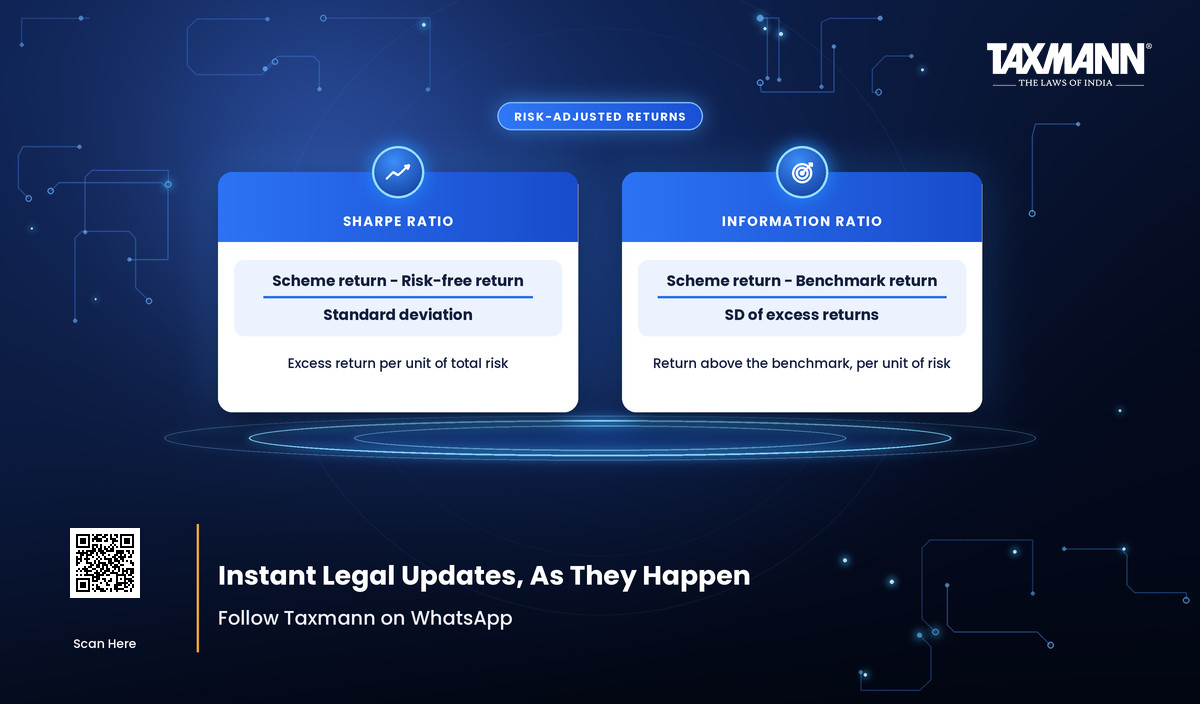
Table of Contents
- Why raw return is not enough
- The Sharpe Ratio
- The Information Ratio
- Sharpe vs Information Ratio
- Quick answers
1. Why raw return is not enough
A scheme returning 12% by taking wild risks is not obviously better than one returning 10% steadily. Risk-adjusted measures exist to answer the real question: how much return did the manager earn for the risk they took?
2. The Sharpe Ratio
Start with the alternative. An investor can lend to the government and earn a risk-free return (Rf)—the T-Bill index is a good proxy. By investing in a scheme instead, they take risk and earn a scheme return (Rs).
The difference, Rs − Rf, is the risk premium—the reward for taking risk rather than staying risk-free. The Sharpe Ratio compares that premium to the risk actually taken, using standard deviation as the risk measure.
Worked example. Risk-free return is 5%. A scheme with a standard deviation of 0.5% earned 7%.
Sharpe Ratio = (7% − 5%) ÷ 0.5% = 4
Interpretation: the Sharpe Ratio is the risk premium generated per unit of risk assumed. The higher the Sharpe Ratio, the better the scheme is considered to be.
3. The Information Ratio
The Information Ratio asks a different question: not “how did you do against cash?” but “how did you do against your benchmark, and how consistently?”
It is an established measure of a portfolio manager’s skill and ability to generate excess returns relative to a benchmark, adjusted for risk. By putting the standard deviation of the excess return in the denominator, it also captures the consistency of performance—not just its size.
The disclosure rule most investors don’t know
- It is mandatory for AMCs to disclose the Information Ratio.
- It is the only measure of risk-adjusted return that is mandatory to disclose.
- AMCs must disclose it on their website on a daily basis.
- It is also available on the AMFI website in a comparable format—so you can compare schemes on a like-for-like basis.
- The benchmark used must be the scheme’s tier-1 benchmark, as disclosed in the SID.
That last point matters: because the benchmark and format are prescribed, the Information Ratio is one of the few genuinely comparable numbers across fund houses.
4. Sharpe vs Information Ratio
| Sharpe Ratio | Information Ratio | |
|---|---|---|
| Compares return against | The risk-free rate | The scheme’s benchmark |
| Risk measure used | Standard deviation of returns | Standard deviation of excess return |
| Answers | Reward per unit of total risk | Manager skill & consistency vs benchmark |
| Mandatory disclosure? | No | Yes—daily, on the AMC website |
| Where to find it | Factsheets | AMC website daily; AMFI in comparable format |
A caution on Sharpe comparisons: they are meaningful between comparable schemes. Comparing the Sharpe Ratio of an equity fund with a liquid fund tells you very little.
Chapter 7 of the Mutual Fund Foundation workbook sets out both ratios with formulae and worked examples, and follow-up questions can go to Taxmann AI.
5. Quick answers
What is the Sharpe Ratio formula?
(Scheme return − Risk-free return) ÷ Standard deviation.
Is a higher Sharpe Ratio better?
Yes—it means more risk premium per unit of risk.
What is the Information Ratio?
(Portfolio return − Benchmark return) ÷ Standard deviation of excess return.
Which risk-adjusted measure must AMCs disclose?
The Information Ratio—and it is the only one mandatory to disclose. It must be published daily on the AMC’s website.
Which benchmark is used for the Information Ratio?
The scheme’s tier-1 benchmark, as disclosed in the SID.
Law stated as on 16 November 2026. This article draws on Chapter 7 of the official NISM-Series-V-B Mutual Fund Foundation workbook (March 2026 Workbook Version), published exclusively by Taxmann, read with the law in force on that date. It is general information, not investment, tax or legal advice.
More in this series: What is a Mutual Fund · How Mutual Fund Returns Are Calculated · Types of Mutual Funds · NAV in Mutual Funds · NISM-Series-V-B Exam
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


