[Analysis] NFO in Mutual Funds – Key Dates | 15-Day Window | Re-opening at NAV
- Blog|Company Law|
- 3 Min Read
An NFO is a scheme’s first offer to the public. Here are the three dates that define it, and how pricing works after it closes.
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

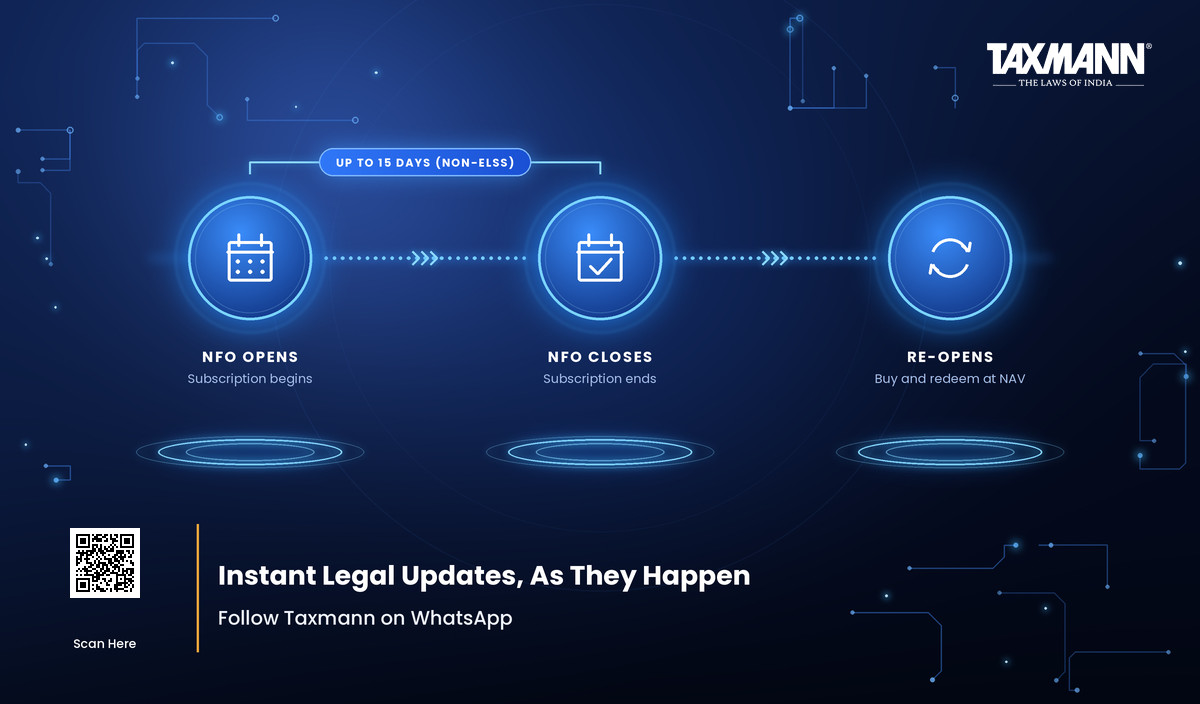
Table of Contents
- The three dates that define an NFO
- Close-ended schemes work differently
- How long can an NFO stay open?
- NFO price vs ongoing price
- Practical points
- Is an NFO a “cheap” entry?
- Quick answers
1. The three dates that define an NFO
For an open-ended scheme, three dates matter:
| Date | What it means |
|---|---|
| NFO Open Date | The date from which investors can invest in the NFO |
| NFO Close Date | The last date to invest in the NFO |
| Scheme Re-opening Date | The date from which investors can buy new units (at the sale price) or offer units for repurchase (at the repurchase price) |
From the re-opening date, the AMC transacts at NAV-based prices.
2. Close-ended schemes work differently
A close-ended scheme has an NFO Open Date and an NFO Close Date—but no Scheme Re-opening Date, because the scheme does not sell or repurchase units after the NFO. To buy or sell, investors must go to the stock exchange where the scheme is listed.
That is a materially different liquidity proposition, and it deserves a moment’s thought before you invest.
3. How long can an NFO stay open?
Under SEBI guidelines, NFOs other than ELSS can remain open for a maximum of 15 days.
4. NFO price vs ongoing price
- NFO price—the price per unit paid during the NFO.
- Ongoing price—the price at which an investor purchases, or receives on redemption or switch-out, once the scheme has re-opened. This is NAV-based.
5. Practical points
- Scheme documents and application forms are circulated to market intermediaries so investors can apply during the NFO.
- An SIP can be initiated during an NFO—you don’t have to wait for the scheme to re-open.
6. Is an NFO a “cheap” entry?
Be careful with that instinct. An NFO is a new scheme, not a discounted one—the NFO price is a starting price, not a bargain. What you should be evaluating is the same as for any scheme: the investment objective, the asset allocation, the risk profile, the expenses and the suitability for your goal. All of that sits in the scheme documents, and the KIM that accompanies the application form.
Before investing in an NFO, read the scheme documents; our guide to SID, SAI and KIM explains each. SEBI’s rules are on Taxmann.com | Research, and the NFO process is covered in Chapter 9 of the Mutual Fund Foundation workbook.
7. Quick answers
What is the full form of NFO?
New Fund Offer.
How long can an NFO remain open?
A maximum of 15 days, for NFOs other than ELSS.
What are the three NFO dates?
NFO Open Date, NFO Close Date and Scheme Re-opening Date.
Do close-ended schemes have a re-opening date?
No. After the NFO, you must buy or sell on the stock exchange where the scheme is listed.
Can I start an SIP during an NFO?
Yes.
Law stated as on 16 November 2026. This article draws on Chapters 9 and 2 of the official NISM-Series-V-B Mutual Fund Foundation workbook (March 2026 Workbook Version), published exclusively by Taxmann, read with the law in force on that date. It is general information, not investment, tax or legal advice.
More in this series: What is a Mutual Fund · SID, SAI and KIM · NAV in Mutual Funds · KYC for Mutual Fund Investors · SIP, SWP and STP
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


