[Analysis] SID, SAI and KIM – Mutual Fund Scheme Documents | What Each Contains | Vetted, Not Approved
- Blog|Company Law|
- 4 Min Read
Three documents govern every mutual fund scheme. Here’s what each one is for—and why “SEBI approved” is a phrase you should never trust.
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

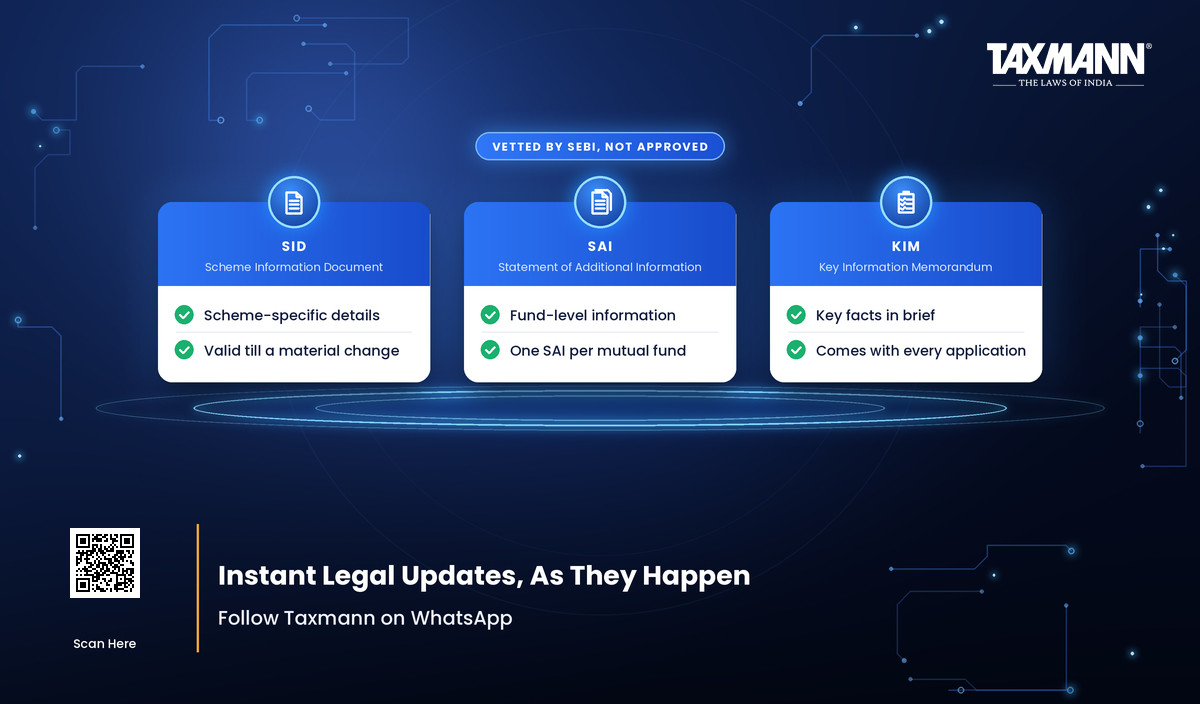
Table of Contents
- Why these documents legally matter
- The three documents
- The phrase you should never trust: “SEBI approved”
- Where to find them
- What’s inside the SAI
- What’s inside the KIM
- And the Addendum
- How long does a SID stay valid?
- Quick answers
1. Why these documents legally matter
Units are offered to you through the scheme documents. By signing the application form and paying, you accept the offer; by issuing units, the fund completes the contract.
The consequence is sharp: an investor cannot claim, at a future date, to have been unaware of a fact that was disclosed in the scheme related documents. Signing means you have legally accepted the terms. That is the strongest possible argument for reading them.
2. The three documents
| Document | Covers | Scope |
|---|---|---|
| SID | The particular scheme—what a prospective investor ought to know before investing | One per scheme |
| SAI | Statutory information about the mutual fund / AMC offering the scheme | One SAI for all schemes of a mutual fund |
| KIM | A summary of the SID and SAI | Must accompany every application form |
A legal nicety worth knowing: in practice SID and SAI are two separate documents, though the legal technicality is that the SAI is part of the SID.
3. The phrase you should never trust: “SEBI approved”
Both SID and SAI are prepared in SEBI’s prescribed format, with contents flowing in the prescribed sequence, and submitted to SEBI. The fund may add any further disclosure it considers material for the investor.
But here is the point most people get wrong:
Anyone selling you a “SEBI-approved scheme” is misdescribing the position.
Because investors are not experts in finance or law, the documents must be written in simple, clear, concise and easy-to-understand language.
4. Where to find them
- Draft SID and SAI are public documents, viewable on SEBI’s website.
- Final documents (after SEBI’s observations are incorporated) must be hosted on the AMFI website two days before the issue opens.
- Every mutual fund provides downloads of these documents for all its current schemes on its own website.
- Investors have a right to ask for a printed copy of the SAI.
5. What’s inside the SAI
| Content | What it gives you |
|---|---|
| Constituents of the mutual fund | Full details of sponsors, AMC, trustee company, and service providers (custodian, RTA, statutory auditor, fund accountant if outsourced, collecting bankers)—including experience, condensed financials for schemes launched in the last 3 financial years, and key personnel |
| How to apply | Application guidance |
| Rights of unit-holders | Beneficial ownership of scheme assets, servicing timelines, right to information and disclosures, right to exit on scheme changes |
| Investment valuation norms | How each type of security is valued—standardised by SEBI |
| Tax, legal & general information | Nomination, transfer and transmission, investment by minors, pledge/lien, taxation |
| Investor grievance | How to register a complaint |
6. What’s inside the KIM
The KIM exists for a practical reason: circulating full documents with every printed application form is difficult and costly. So SEBI mandates that every application form be accompanied by a KIM—the key points needed to judge suitability.
It contains: the names of the AMC, mutual fund, trustee, fund manager and scheme; the issue opening, closing and re-opening dates; the investment objective; the asset allocation pattern; the risk profile (risk to principal, suitable investment horizon, types of securities); plans and options; the benchmark index; the IDCW plan; performance of the scheme and benchmark over 1, 3 and 5 years and since inception; the expenses; and how to register grievances.
7. And the Addendum
SID, SAI and KIM are updated periodically—but interim changes are communicated through an Addendum. An addendum is considered part of the scheme related documents and must accompany the KIM. If you’re reading a KIM without its addenda, you’re reading an incomplete document.
8. How long does a SID stay valid?
A SID remains effective until a ‘material change’ occurs (other than a change in fundamental attributes and within the SID’s purview). Changes are then filed with SEBI and communicated to investors, or publicly notified by newspaper advertisement, subject to the applicable regulations.
SEBI’s rules on scheme documents are on Taxmann.com | Research, and follow-up questions can go to Taxmann AI. Scheme documents are Chapter 5 of the Mutual Fund Foundation workbook, worth 12% of the exam.
9. Quick answers
What is the full form of SID, SAI and KIM?
Scheme Information Document, Statement of Additional Information and Key Information Memorandum.
Does SEBI approve mutual fund scheme documents?
No. SEBI issues observations that the fund must incorporate—the documents are vetted, not approved.
How many SAIs does a mutual fund have?
One—a single SAI covers all the schemes offered by that mutual fund.
Must the KIM accompany the application form?
Yes—SEBI regulations require every application form to be accompanied by the KIM.
What is an addendum?
The document used to communicate interim changes. It is part of the scheme related documents and must accompany the KIM.
Can I say I didn’t know something disclosed in the SID?
No. Signing the application form means you have legally accepted the disclosed terms.
Law stated as on 16 November 2026. This article draws on Chapter 5 of the official NISM-Series-V-B Mutual Fund Foundation workbook (March 2026 Workbook Version), published exclusively by Taxmann, read with the law in force on that date. It is general information, not investment, tax or legal advice.
More in this series: What is a Mutual Fund · NFO in Mutual Funds · Who Regulates Mutual Funds in India · Types of Mutual Funds · Expense Ratio (TER) in Mutual Funds
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


