Section 115H is now section 217 of the Income-tax Act 2025. Which Act decides an NRI’s residence each year, sections 213 to 216, and the 115F claw-back.
Tag: Residential Status
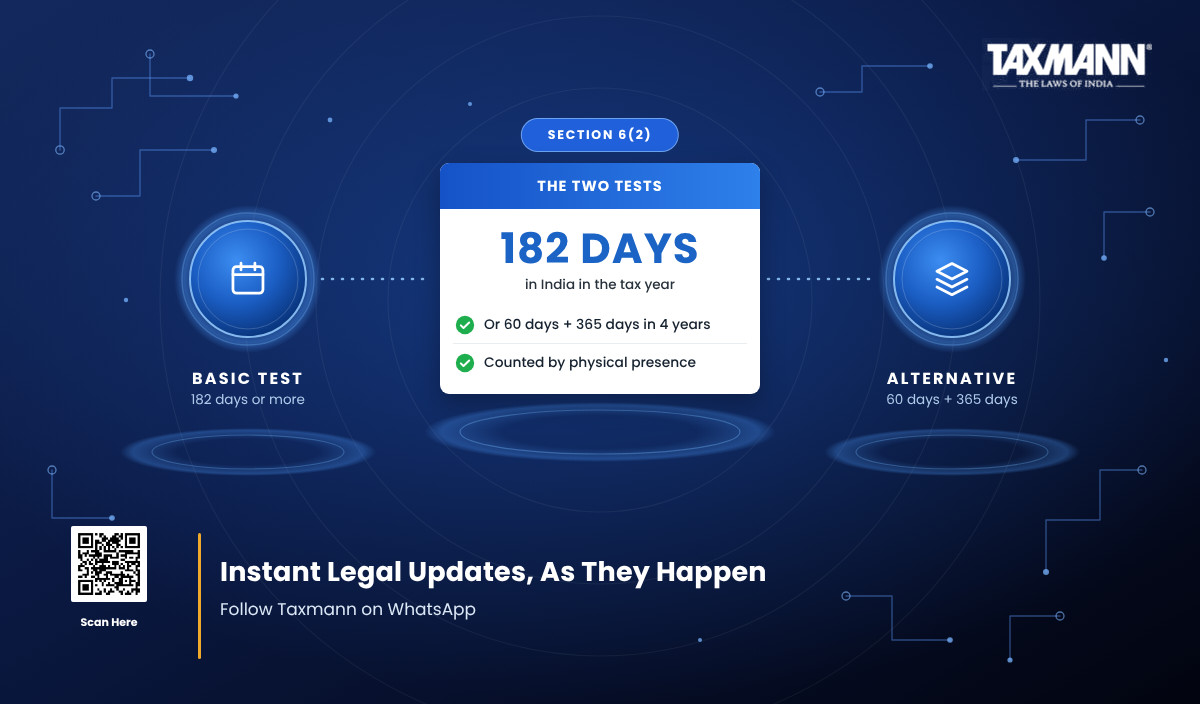
Residential status of an individual under section 6(2): the 182-day test, whether the arrival date counts, the employment relief and the Rs. 15 lakh rule.
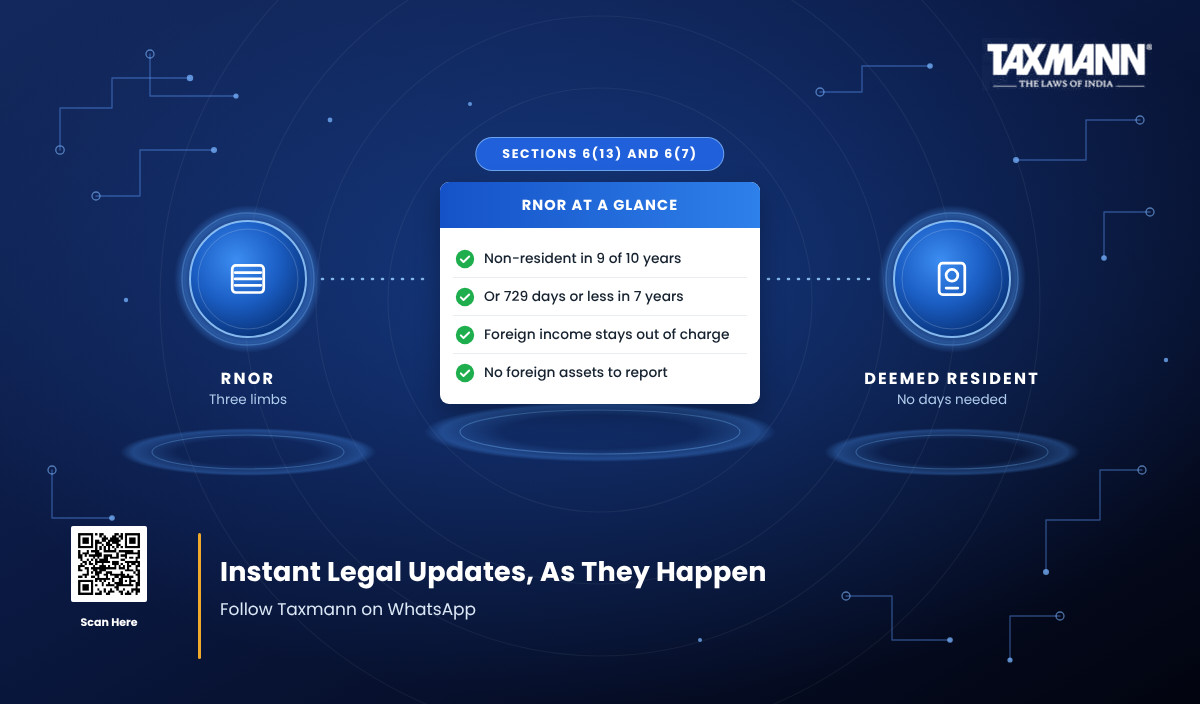
RNOR status under section 6(13) and deemed residency under section 6(7): the three limbs, what RNOR is worth, the karta problem, withholding and the TRC.
Tax residency certificate under section 159(8): what it proves after Tiger Global (SC, 15 January 2026), and why Rule 75 now needs Form 41 in every claim.
Residential status of a company under section 6(10): Indian company, place of effective management, the CBDT Guiding Principles, and incidence of tax.
Table of Contents 1. Residence … Continue reading “Overview of Tax Residence in India under Income Tax”
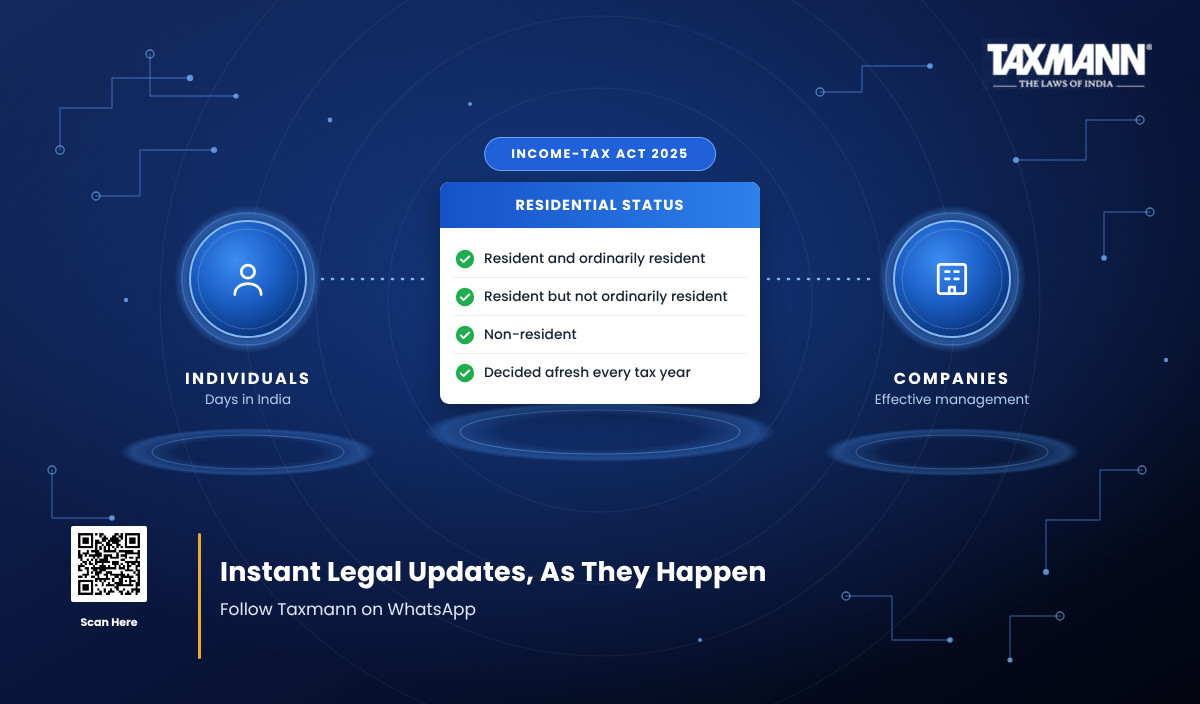
Residential status in income tax under section 6 of the Income-tax Act 2025: the 182-day test, RNOR, deemed resident, company POEM and what each changes.









 CA | CS | CMA


