[Analysis] Residential Status of an Individual – Section 6(2) | The 182-Day Test | How Days Are Counted
- Blog|Income Tax|
- 10 Min Read
Residential status of an individual under section 6(2): the 182-day test, whether the arrival date counts, the employment relief and the Rs. 15 lakh rule.
- By Taxmann
- |
- Last Updated on 18 November, 2026
Latest from Taxmann

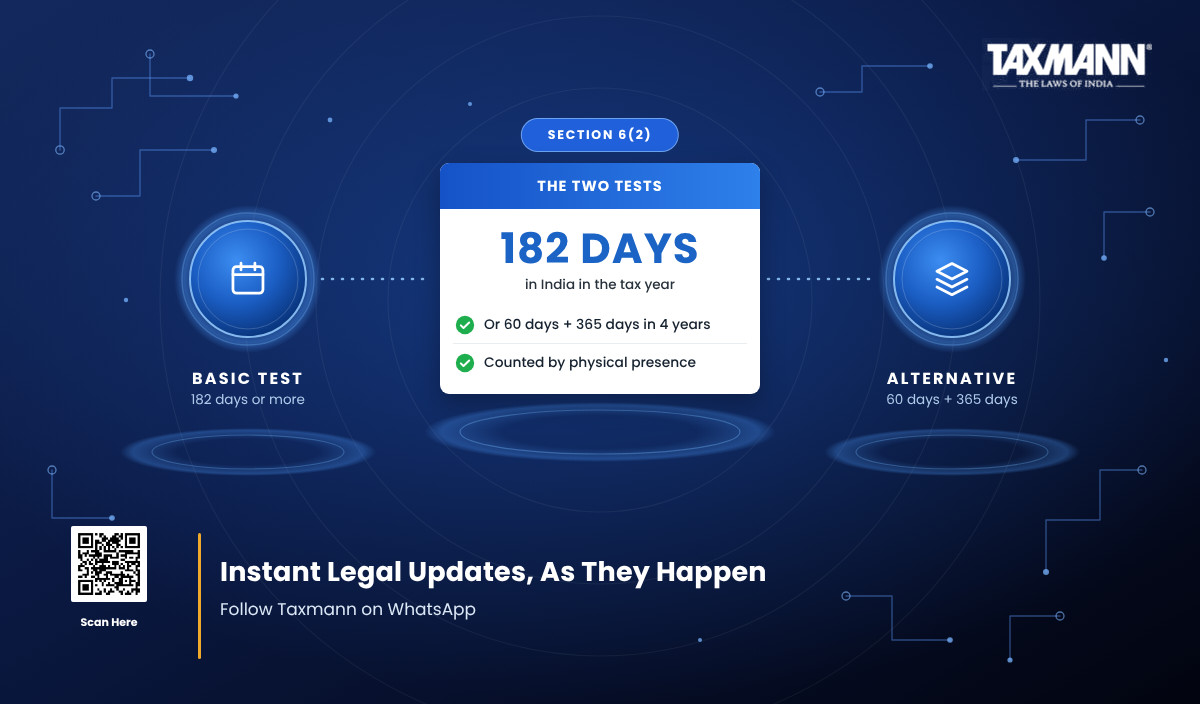
Table of Contents
- When is an individual resident in India under the Income-tax Act 2025?
- How the 182 days are counted [Section 6(2)(a)]
- Does the date of arrival count? The authorities do not agree
- What the words ‘day’ and ‘year’ mean
- The alternative test: 60 days plus 365 days [Section 6(2)(b)]
- When the 60-day test is switched off [Sections 6(3) and 6(4)]
- What ‘leaves India for the purposes of employment’ means
- Crew members of a foreign-bound ship [Section 6(6) and Rule 8]
- The fifteen-lakh threshold for visiting citizens and persons of Indian origin
- What evidence proves the day count
- Quick answers
1. When is an individual resident in India under the Income-tax Act 2025?
An individual is resident in India in a tax year if he is in India for a total period of 182 days or more in that year, or if he is in India cumulatively for 60 days or more in that year and cumulatively for 365 days or more in the four preceding years. Either limb of section 6(2) makes him resident.
The Assessing Officer is not free to stop at the first. In Vijay Mallya v. Asstt. CIT [2003] 131 taxman 477 (Cal), the Calcutta High Court treated the examination of both clauses as a mandatory requirement of law: a person who is not resident under the 182-day limb may still be resident under the alternative one.
2. How the 182 days are counted [Section 6(2)(a)]
By actual physical presence in India, aggregated across the tax year. The stay need not be continuous. Section 6(2)(a) uses the phrase “is in India for a total period”, and every spell of presence during the year is added together to test the 182-day threshold.
The wording changed at the margin. The Income-tax Act 1961 said “period or periods amounting in all”; the 2025 Act says “total period”. The older formula prescribed the method of aggregation, the newer one states the result. Nothing in the change alters the arithmetic.
What it does not permit is aggregation across years. Section 6(2)(a) tests presence “in that year”, and that year is the tax year. A stay from 15 November 2025 to 15 June 2026 runs to 213 days end to end and still fails the test twice: 137 days fall in financial year 2025-26 and 76 days in tax year 2026-27. Seven unbroken months in India, non-resident in both years.
3. Does the date of arrival count? The authorities do not agree
They do not, and the difference decides cases. On an identical set of flights, counting the date of arrival or leaving it out can move a taxpayer across the 182-day line without a single travel plan changing.
Take an individual with seven separate visits in financial year 2025-26:
| Arrival | Departure | Days excluding arrival date | Days including arrival date |
|---|---|---|---|
| 07.04.2025 | 03.05.2025 | 26 | 27 |
| 21.05.2025 | 19.06.2025 | 29 | 30 |
| 14.07.2025 | 08.08.2025 | 25 | 26 |
| 02.09.2025 | 27.09.2025 | 25 | 26 |
| 19.10.2025 | 15.11.2025 | 27 | 28 |
| 08.12.2025 | 04.01.2026 | 27 | 28 |
| 09.02.2026 | 25.02.2026 | 16 | 17 |
| Total | 175 | 182 | |
On the left-hand count he is a non-resident. On the right-hand count he is exactly at the threshold, and the section says “182 days or more”. Seven arrival dates are the whole of the difference.
The Tribunal has repeatedly excluded the day of arrival. It did so in Pradeep Kumar Joshi v. ITO (IT) [2021] 133 taxmann.com 283 (Ahmedabad – Trib.), following Manoj Kumar Reddy v. ITO (IT) [2009] 34 SOT 180 (Bangalore), and criticised the Commissioner (Appeals) for having included the arrival date without justification. The Delhi Bench reached the same conclusion in Sanjay Bhaskar v. Dy. CIT [2026] 182 taxmann.com 66 (Delhi – Trib.), following the Karnataka High Court in DCIT (IT) v. Manoj Kumar Reddy [2011] 12 taxmann.com 326. The decision can be relied on to exclude the day of arrival, particularly where the arrival is late in the day.
Against that stands the Authority for Advance Rulings. In Advance Ruling P. No. 7 of 1995, In re [1997] 90 Taxman 62, an applicant who had entered and left India on 22 occasions put his presence at 178 days by excluding arrival and departure days and at 198 days by including them. The Authority declined to accept the exclusion: what section 6(2)(a) counts is the number of days on which the applicant was present in India, and the days of entry and exit must be taken into account. The Commentary on Article 15 of the OECD Model, dealing with the cognate 183-day test, endorses only the “days of physical presence” method, which counts part of a day, the day of arrival and the day of departure alike.
A middle position exists. ITO (IT) v. Fausta C. Cordeiro [2012] 24 taxmann.com 193 (Mumbai) disregarded the day of arrival where the arrival was late at night, but counted it where the arrival was early in the morning. That reading turns on an hour the immigration stamp does not record, since the passport is stamped well after landing and well before departure; the time on the travel ticket is the better evidence.
The point is unresolved. Document the assumption on which a return is filed rather than discover it in an assessment.
4. What the words ‘day’ and ‘year’ mean
A “day” is the period from midnight to midnight, and it includes weekends and public holidays. Neither Act defines the word, so the ordinary legal meaning applies.
There is a statutory argument for excluding the first day, and it comes from outside the Income-tax Act. Counting a period of stay requires the words “from” and “to”, which section 6(2) does not supply. Section 9 of the General Clauses Act provides that “from” excludes the first day in a series and “to” includes the last. Import those words to do the arithmetic and the first day drops out with them.
“Year”, where the section speaks of four preceding years under section 6(2)(b) or seven under section 6(13), means periods of twelve calendar months each immediately preceding the start of the relevant tax year, not periods ending on the preceding 31 December: CIT v. V. E.K.R. Savumiamurthy [1946] 14 ITR 185 (Mad).
5. The alternative test: 60 days plus 365 days [Section 6(2)(b)]
Section 6(2)(b) [corresponding to section 6(1)(c) of the Income-tax Act 1961] makes an individual resident if he is in India cumulatively for 60 days or more in the tax year and cumulatively for 365 days or more in the four years preceding it. Both conditions must hold. In substance it is a five-year test: the tax year plus the four before it.
The threshold is low enough to catch people who do not think of themselves as resident. An individual in India for 100 days a year, every year, satisfies both conditions and is resident, though he has never come close to 182 days in any single year.
6. When the 60-day test is switched off [Sections 6(3) and 6(4)]
Section 6(2)(b) does not apply to two classes of person. Section 6(3) disapplies it for a citizen of India who leaves India in any tax year as a member of the crew of an Indian ship, as defined in section 3(18) of the Merchant Shipping Act 1958, or for the purposes of employment outside India. Section 6(4) disapplies it for a citizen of India or a person of Indian origin who, being outside India, comes on a visit to India. For anyone in either class, residence turns on the 182-day limb alone.
Which year does section 6(3) speak of? It says “any tax year”, where section 6(2) says “in that year”. In Manoj Kumar Reddy v. ITO (IT) [2009] 34 SOT 180 (Bangalore) the relief was read as applying to the tax year in which the citizen actually leaves India, and not at large.
Section 6(4) is narrower than it looks. “Being outside India” and “comes on a visit to India” are read together, and together they describe someone whose settled presence is abroad and whose presence in India is occasional. The Madras High Court in Asstt. DCIT v. Apparasu Ravi [2011] 10 taxmann.com 200 examined the nature and purpose of the visit and the visa issued by the foreign country, not duration alone. In ADIT v. Sudhir Choudhrie [2017] 88 taxmann.com 570 (Delhi – Trib.), proving “being outside India” meant establishing that the centre of vital interests, personal and economic, lay in another country. And in Binny Bansal v. Dy. CIT [2026] 182 taxmann.com 226 (Bangalore – Trib.), an assessee who had been resident in the preceding year could not claim the extended period.
7. What ‘leaves India for the purposes of employment’ means
More than salaried employment. The Supreme Court in CBDT v. Aditya V. Birla [1988] 36 Taxman 9 held that employment is not confined to service under an employer, and CBDT Circular No. 346 dated 30 June 1982 states that no technical meaning is intended for the word. Going abroad to take up a vocation, including self-employment, business or a profession, is enough; the Kerala High Court applied that in CIT v. Abdul Razak [2011] 198 taxman 1/10 taxmann.com 4, where taking up one’s own business abroad satisfied the condition.
What the relief does not cover is travel for tourism, medical treatment or study. Visa type matters for the same reason: a tourist, transit or pass-through visa does not describe a departure for the purposes of employment.
Two refinements belong in the file. Prior employment is irrelevant: in Asstt. CIT v. Raj Jain [2013] 38 taxmann.com 133 (Delhi – Trib.), an assessee already employed in India before moving to the group’s Chinese company still fell within the provision, his stay in India being under 182 days. And the phrase is “for the purposes of employment”, not “in connection with employment”: in ITO v. Dr. M. P. Konanhalli [1995] 55 ITD 266 (Bangalore – Trib.), a person already employed abroad who came to India, stayed a while and left again to rejoin the same employment was held not to be covered.
8. Crew members of a foreign-bound ship [Section 6(6) and Rule 8]
For a citizen of India who is a member of the crew of a foreign-bound ship, section 6(6) provides that the number of days in India for that voyage is determined as prescribed. Rule 8 of the Income-tax Rules 2026 [corresponding to Rule 126 of the Income-tax Rules 1962] does the prescribing: the period from the date of joining the ship for an eligible voyage to the date of signing off, both as entered in the Continuous Discharge Certificate, is excluded from the stay in India.
“Eligible voyage” carries the weight. It means a voyage by a ship carrying passengers or freight in international traffic which either originates at an Indian port and is destined for a port outside India, or originates outside India and is destined for an Indian port. A vessel running Mumbai to Chennai to Kochi and back to Mumbai is on a coastal voyage, and the exclusion does not reach it.
A separate point, often confused with this one: CBDT Circular No. 13/2017 read with Circular No. 17/2017 clarifies that salary accruing to a non-resident seafarer for services rendered outside India on a ship is not brought into total income merely because it was credited to an NRE account with an Indian bank.
9. The fifteen-lakh threshold for visiting citizens and persons of Indian origin
Where a visiting citizen of India or person of Indian origin has total income exceeding Rs. 15,00,000 in the tax year, other than income from foreign sources, section 6(5) substitutes “one hundred and twenty days” for “sixty days” in section 6(2)(b). The relief in section 6(4) narrows; it does not disappear.
“Income from foreign sources” is defined in section 6(14) as income accruing or arising outside India, other than income derived from a business controlled in or a profession set up in India, and which is not deemed to accrue or arise in India. Income caught by the deeming provisions therefore counts towards the threshold, which is how a visitor working remotely from India can breach it on salary alone.
The test is on total income, not gross receipts. A person of Indian origin visiting each year with gross rent of Rs. 18,00,000, NRE interest of Rs. 4,00,000 and a long-term capital gain of Rs. 1,50,000 receives Rs. 23,50,000 and stays below the line:
| Source | Amount (Rs.) | Included in total income (Rs.) |
|---|---|---|
| Rent, gross | 18,00,000 | |
| Less: standard deduction at 30% | 5,40,000 | 12,60,000 |
| NRE account interest | 4,00,000 | |
| Less: exemption under Schedule IV (Table Sl. No. 1) | 4,00,000 | Nil |
| Long-term capital gain | 1,50,000 | 1,50,000 |
| Total income | 14,10,000 |
Computed on receipts he would have been over Rs. 15,00,000, and his permitted stay would have fallen from 182 days to 120. Where the threshold has to be computed rather than estimated, Taxmann’s income tax calculator will do the total-income arithmetic.
10. What evidence proves the day count
The passport, first and foremost. The onus of proving residential status lies on the assessee, and the passport is the primary record of entry into and exit from India.
Where it is lost the position is not hopeless. A missing-passport report, and notarised copies of any surviving pages under the Notaries Act 1952, are the usual substitutes; earlier returns declaring the days of stay, processed under section 143(1) and never taken up for assessment, corroborate. Secondary evidence on these lines was accepted in Asstt. CIT v. Sudhir Sareen [2015] 57 taxmann.com 121 (Delhi – Trib.).
Involuntary presence is a different question, and the answer depends on the kind of compulsion. Business exigency is no answer: a person who stays in India because his business requires it is resident if the conditions are met, whatever his preference. Legal compulsion is another matter. In CIT v. Suresh Nanda [2015] 57 taxmann.com 448 (Delhi), the period during which the assessee’s passport stood impounded was excluded from the count.
Where the dispute is about what the days mean, the section, the rules and the case law on each limb sit in the Income-tax module on Taxmann.com | Research.
11. Quick answers
Is the day of arrival in India counted for the 182-day test?
The Tribunal has held that it is excluded, in Pradeep Kumar Joshi (2021) and Sanjay Bhaskar (2026), the latter following the Karnataka High Court in Manoj Kumar Reddy. The Authority for Advance Rulings took the opposite view in Advance Ruling P. No. 7 of 1995, and the OECD Commentary counts both arrival and departure days. The point is unresolved.
Do the 182 days have to be continuous?
No. Section 6(2)(a) refers to a total period, so separate visits in the same tax year are added together. What cannot be added is presence falling in two different tax years.
Does self-employment abroad count as leaving India for the purposes of employment?
Yes. CBDT v. Aditya V. Birla (SC) and CBDT Circular No. 346 dated 30 June 1982 both treat employment as covering vocation and self-employment. Tourism, medical treatment and study do not qualify.
How is the stay of a seafarer on a foreign-bound ship computed?
The period from joining to signing off for an eligible voyage, as entered in the Continuous Discharge Certificate, is excluded under Rule 8 of the Income-tax Rules 2026. The exclusion applies to international voyages, not coastal ones.
Is the Rs. 15,00,000 threshold tested on gross income?
No. It is tested on total income other than income from foreign sources, so statutory deductions and exemptions reduce it. Income deemed to accrue or arise in India is counted.
What proves the number of days if the passport is lost?
A missing-passport report with notarised copies of any surviving pages, supported by earlier returns declaring the days of stay that were processed and not taken up for assessment. Asstt. CIT v. Sudhir Sareen (Delhi – Trib.) accepted evidence of that kind.
This article draws on Chapter 4 of Taxmann’s Residential Status under Income-tax Act 2025 by CA Sachin Sinha (1st Edition, 2026), which works through the individual tests across twenty-one numbered paragraphs, with the 1961 counterpart mapped alongside each provision. The law is stated as updated till August 2026.
Income-tax Acts and Rules, case laws, circulars and notifications are available on Taxmann.com | Research under Income Tax.
More in this series: Residential status in income tax · RNOR, deemed resident and the stateless person · NRIs and section 115H under the Income-tax Act 2025 · The Tax Residency Certificate after Tiger Global
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


