[Analysis] Residential Status in Income Tax – Section 6 of the Income-tax Act 2025 | Resident | RNOR | Non-Resident
- Blog|Income Tax|
- 7 Min Read
Residential status in income tax under section 6 of the Income-tax Act 2025: the 182-day test, RNOR, deemed resident, company POEM and what each changes.
- By Taxmann
- |
- Last Updated on 18 November, 2026
Latest from Taxmann

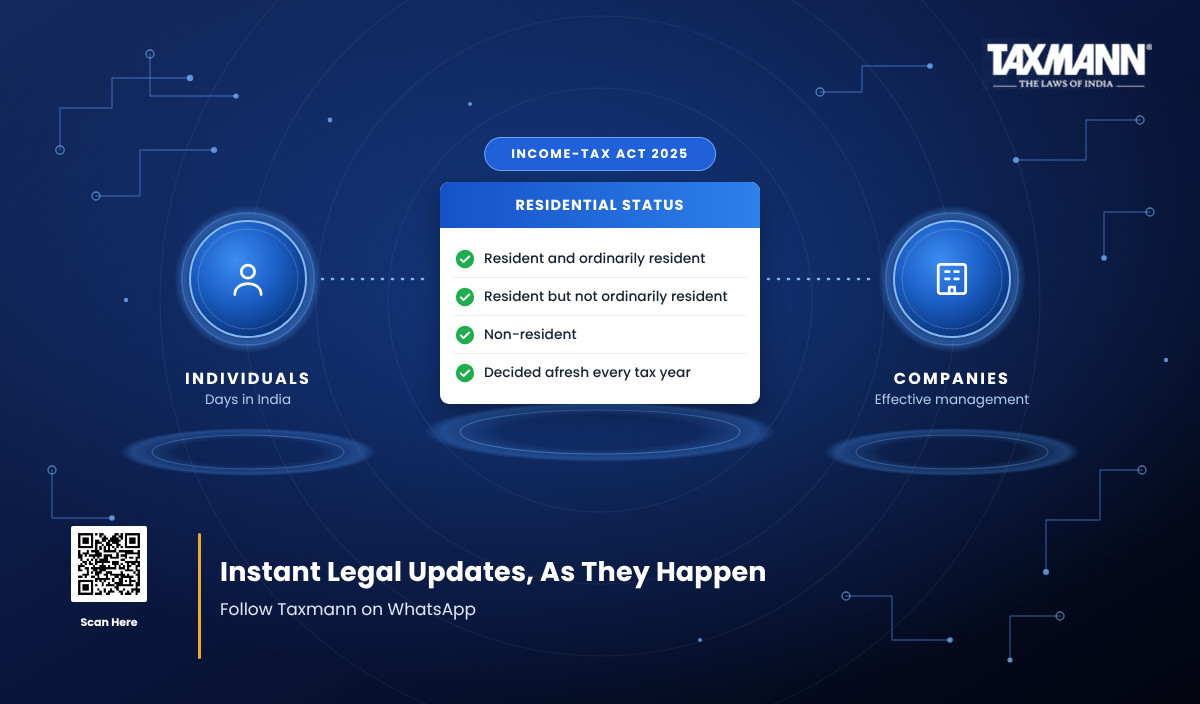
Table of Contents
- What is residential status, and why does it decide your tax
- How the Income-tax Act 2025 fixes residential status [Section 6]
- Residential status of an individual [Section 6(2)]
- When the 60-day test does not apply [Sections 6(3), 6(4) and 6(5)]
- Deemed resident and the stateless person [Section 6(7)]
- Ordinarily resident or not ordinarily resident [Section 6(13)]
- Residential status of an HUF, firm and AOP [Section 6(9)]
- Residential status of a company [Section 6(10)]
- What changes once status is fixed [Section 5]
- Quick answers
1. What is residential status, and why does it decide your tax
Residential status is the test that decides how much of a person’s income India can tax. A resident is taxed on worldwide income. A non-resident is taxed only on income received, accruing or arising in India, or deemed to do so. The status is determined afresh for each tax year.
It is worth being precise about how far the consequences run, because they run further than most summaries suggest. Residential status governs the scope of total income under section 5. It governs entitlement to relief under a Double Taxation Avoidance Agreement, and the tie-breaker that follows when two States both claim a person. It governs the availability of foreign tax credit. It decides which table of section 393 a payer withholds under. It decides whether foreign assets must be reported at all.
Get it wrong and the error is not confined to one line of the return. Everything downstream inherits it.
2. How the Income-tax Act 2025 fixes residential status [Section 6]
Section 6 of the Income-tax Act 2025 determines residential status for every category of person. Sub-sections (2) to (7) deal with individuals, sub-section (9) with a Hindu undivided family, firm or association of persons, and sub-section (10) with companies. Sub-section (13) then splits residents into two classes.
Two definitions sit behind the section. “Resident” means a person who is resident in India within the meaning of section 6 [section 2(96), corresponding to section 2(42) of the Income-tax Act 1961]. “Non-resident” means a person who is not a resident [section 2(72), corresponding to section 2(30)].
One rule is easy to miss. Under section 6(12), if a person is resident in India in a tax year for any source of income, that person is deemed resident for every other source in the same year. Status is not sliced by source.
3. Residential status of an individual [Section 6(2)]
Under section 6(2), an individual is resident in India in a tax year if either of two conditions is met. The first is presence in India for a total period of 182 days or more in that tax year. The second is presence for 60 days or more in that year, combined with 365 days or more across the four preceding years.
The two limbs are joined by “or”. They are alternatives, not cumulative. An individual who fails the first can still be resident under the second, and the assessing officer is expected to test both.
| Test | Condition | Provision |
|---|---|---|
| Basic test | 182 days or more in India in the tax year | Section 6(2)(a) |
| Alternative test | 60 days or more in the tax year and 365 days or more in the four preceding years | Section 6(2)(b) [corresponding to section 6(1)(c) of the Income-tax Act 1961] |
Counting the days is less mechanical than it looks. Whether the date of arrival is included can move a total across the threshold on the same travel schedule, and the authorities are not aligned on the point. That question is worked through separately in our post on the 182-day test and how days are counted.
4. When the 60-day test does not apply [Sections 6(3), 6(4) and 6(5)]
The 60-day limb is switched off in two situations. Section 6(3) disapplies it for a citizen of India who leaves India in any tax year either as a member of the crew of an Indian ship, as defined in section 3(18) of the Merchant Shipping Act 1958, or for the purposes of employment outside India. Section 6(4) disapplies it for a citizen of India or a person of Indian origin who, being outside India, comes to India on a visit.
The second relaxation is qualified. Where the visiting individual has total income exceeding Rs. 15,00,000 during the tax year, other than income from foreign sources, section 6(5) substitutes “one hundred and twenty days” for “sixty days”. The relaxation narrows rather than disappears.
“Income from foreign sources” is defined in section 6(14) as income accruing or arising outside India, other than income derived from a business controlled in or a profession set up in India, and which is not deemed to accrue or arise in India. Income falling within the deeming provisions therefore counts towards the fifteen-lakh threshold.
5. Deemed resident and the stateless person [Section 6(7)]
Section 6(7) makes an individual resident irrespective of days spent in India. It applies where the individual is a citizen of India, is not liable to tax in any other country or territory by reason of domicile, residence or criteria of a similar nature, and has total income exceeding Rs. 15,00,000 during the tax year other than income from foreign sources.
This is an anti-abuse provision, carried forward from section 6(1A) of the Income-tax Act 1961. It targets the individual who has arranged matters so as to be taxable nowhere. Note what it does not require: the person need not have set foot in India during the year at all.
6. Ordinarily resident or not ordinarily resident [Section 6(13)]
Once a person is resident, section 6(13) decides whether they are ordinarily resident or not ordinarily resident. The distinction matters because a resident but not ordinarily resident is not taxed on foreign income unless it is derived from a business controlled in or a profession set up in India.
A person is not ordinarily resident where any of three limbs is satisfied:
| Limb | Condition |
|---|---|
| Section 6(13)(a) | The individual, or the manager of the HUF, has been a non-resident in nine out of the ten preceding tax years, or has been in India for 729 days or less across the seven preceding tax years |
| Section 6(13)(b) | A citizen of India or person of Indian origin whose total income excluding foreign-source income exceeds Rs. 15,00,000, and who was in India for 120 days or more but less than 182 days in the tax year |
| Section 6(13)(c) | A citizen of India deemed resident under section 6(7) |
Section 6(13) corresponds to section 6(6) of the Income-tax Act 1961, and the substantive conditions are unchanged.
7. Residential status of an HUF, firm and AOP [Section 6(9)]
A Hindu undivided family, firm or other association of persons is resident in India in any tax year unless the control and management of its affairs is situated wholly outside India during that year. The presumption runs towards residence, and the burden of displacing it is real.
Two words carry the weight. “Control and management” means de facto control actually exercised, not the legal right to control. And “wholly” means what it says: if the seat of control and management is in more than one place and any one of them is in India, the entity is resident. Partial control in India is enough.
8. Residential status of a company [Section 6(10)]
A company is resident in India in a tax year if it is an Indian company, or if its place of effective management is in India in that year. An Indian company is always resident, whatever the location of its management.
Place of effective management is defined in section 6(10)(b) as the place where key management and commercial decisions that are necessary for the conduct of the business of an entity as a whole are, in substance, made. The provision corresponds to section 6(3) of the Income-tax Act 1961. Because the test turns on substance, it is decided on the facts of each year, and a company’s place of effective management must be evaluated afresh every tax year.
9. What changes once status is fixed [Section 5]
Section 5 sets the scope of total income by reference to status. A resident is taxed on income received or deemed received in India, income accruing or arising or deemed to accrue or arise in India, and income accruing or arising outside India. A non-resident is taxed only on the first two.
| Status | Indian income | Foreign income |
|---|---|---|
| Resident and ordinarily resident | Taxable | Taxable |
| Resident but not ordinarily resident | Taxable | Taxable only if derived from a business controlled in or a profession set up in India [section 5(1)(c)] |
| Non-resident | Taxable | Not taxable |
For the bare text of section 6, the case law on each limb and the CBDT circulars that sit behind it, see the Income-tax module on Taxmann.com | Research. Where the same question has to be answered across the Income-tax module and the practice material at once, Taxmann.com | Premium carries both.
10. Quick answers
Is residential status the same as citizenship?
No. Citizenship is a question of nationality law. Residential status is decided under section 6 by presence in India and, for entities, by control and management or place of effective management. A foreign citizen can be resident in India, and an Indian citizen can be a non-resident.
Is residential status decided once, or every year?
Every tax year, separately. A person resident in one year is not automatically resident in the next. Both limbs of section 6(2) must be applied afresh each year.
Does the 182-day period have to be continuous?
No. Section 6(2)(a) refers to a total period. Separate spells of presence in the same tax year are aggregated.
What is the benefit of being a resident but not ordinarily resident?
Foreign income falls outside the scope of total income unless it is derived from a business controlled in or a profession set up in India. A person in this category is also not required to report foreign assets in the return.
Can a person be deemed resident without visiting India?
Yes. Section 6(7) operates irrespective of days in India, provided the individual is an Indian citizen, is not liable to tax in any other country by reason of domicile, residence or similar criteria, and has non-foreign-source income above Rs. 15,00,000.
From which year does the Income-tax Act 2025 govern residential status?
For tax years beginning on or after 1 April 2026. Status for earlier years continues to be determined under section 6 of the Income-tax Act 1961, even if the assessment or reassessment happens later.
This article draws on Taxmann’s Residential Status under Income-tax Act 2025 by CA Sachin Sinha (1st Edition, 2026), which examines section 6 of the Income-tax Act 2025 phrase by phrase and maps each provision to its counterpart in the Income-tax Act 1961. The law is stated as updated till August 2026.
Income-tax Acts and Rules, case laws, circulars and notifications are available on Taxmann.com | Research under Income Tax.
More in this series: The 182-day test and how days are counted · Residential status of a company and place of effective management · RNOR, deemed resident and the stateless person · The Tax Residency Certificate after Tiger Global · NRIs and section 115H under the Income-tax Act 2025
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
One thought on “[Analysis] Residential Status in Income Tax – Section 6 of the Income-tax Act 2025 | Resident | RNOR | Non-Resident”
Leave a Reply
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


Excellent post, Very informative.