[Analysis] 194J New Section under the Income-tax Act 2025 – Where It Sits | Finding Any New Section | Citing Older Rulings
- Blog|Income Tax|
- 4 Min Read
Section 194J now sits in section 393(1) of the Income-tax Act 2025, read with section 402. Where it sits, how to find the new section for any 1961 one, and how to cite rulings under the old number.
- By Taxmann
- |
- Last Updated on 18 November, 2026
Latest from Taxmann

Law stated as on 18 November 2026.
Table of Contents
- Where section 194J sits now
- How to find the new section for any 1961 section
- Citing rulings that name the old sections
- Both Income-tax Acts, side by side
- Frequently asked questions
1. Where section 194J sits now
The Income-tax Act, 2025 applies from 1 April 2026, and earlier years still bring up the Income-tax Act, 1961. Section numbers have changed, and older rulings cite the old sections.
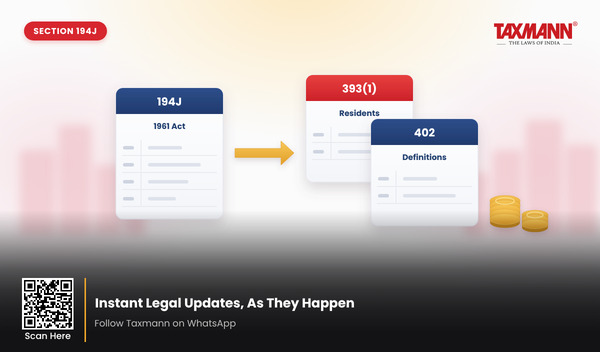
Section 194J shows how far the numbers moved. The 194 series no longer exists as separate sections: the deduction on fees for professional or technical services is now a row in the table in section 393(1), for payments to residents, and the terms it uses, such as “professional services” and “fees for technical services”, are defined in section 402. One 1961 section now sits across two 2025 sections.
For tax year 2025-26 and earlier years, though, the old number is still the one to use: CBDT’s FAQs on section 536 keep proceedings for those years under the 1961 Act, and tax year 2026-27 onwards falls under the 2025 Act. Our analysis of the Income-tax Act 2025 vs 1961 sets out which Act applies to which year.
2. How to find the new section for any 1961 section
Much of the 1961 Act carried over to new numbers, and one old section can sit across more than one new one, as 194J does. A reliable way to work:
- Start from the section you know, and find its counterpart in the 2025 Act.
- Read the counterpart sub-section by sub-section, because a change of words can change the answer.
- Check the matching Rule too, in the Rules of 1962 and 2026.
- Check the CBDT circulars and notifications on the provision, and which Act each one relates to.
3. Citing rulings that name the old sections
Most rulings you will cite were decided under the 1961 Act and use its section numbers. Before you cite one in a matter under the 2025 Act, compare the provision it interpreted with its 2025 counterpart. Where the wording carries over, the ruling is a strong starting point; where it changed, read the ruling with care.
Then check the ruling’s own history: whether later courts followed it, distinguished it, or reversed or overruled it.
A quick check before you rely on a section:
- Which Act governs the proceeding, and for which tax year?
- Which section of that Act, and what is its counterpart in the other?
- Do the rulings you cite interpret the same words?
- Which circulars and notifications apply, and under which Act?
4. Both Income-tax Acts, side by side
Taxmann.com | Research keeps both Acts, and both sets of Rules, side by side.
- Comparative (Act): each section beside its counterpart, sub-section by sub-section, with a note on what changed.
- Comparative (Rules): the Rules of 1962 and 2026, paired.
- Each document says which Act it relates to.
- 92,900+ Income Tax case laws with headnotes, the In Favour of filter and Judicial Analysis, which flags a ruling later reversed or overruled.
- 16,900+ CBDT circulars and notifications, linked to the provisions they interpret.
- All About™ Income-tax Act: the Rules, circulars, notifications, case laws and articles for a section, in one view.
Open Income Tax, Comparative (Act), search 194J: section 194J of the 1961 Act maps to sections 393 and 402 of the 2025 Act, with a table and a note on changes.
5. Frequently asked questions
Where is section 194J in the Income-tax Act, 2025?
In the table in section 393(1), for payments to residents, read with the definitions in section 402. Comparative (Act) in Taxmann.com | Research maps section 194J of the 1961 Act to sections 393 and 402 of the 2025 Act.
How do I find the new section for a 1961 section?
Start from the section you know, find its counterpart in the 2025 Act and read it sub-section by sub-section, with the matching Rule and circulars. Comparative (Act) in Taxmann.com | Research sets each section beside its counterpart.
Can I still cite rulings decided under the 1961 Act?
Yes, as a starting point where the 2025 provision carries the same words. Compare the provision the ruling interpreted with its counterpart first, and check how later courts treated the ruling.
Try Taxmann.com | Research free for 7 days
One trial per person in each product. Trial access is usually read-only, and printing and downloading may be off. A new trial is possible after 12 months.
Related reading: Section 393 of the Income-tax Act 2025 · Section 536 of the Income-tax Act 2025 · Income-tax Act 2025 vs Income-tax Act 1961.
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.
Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


