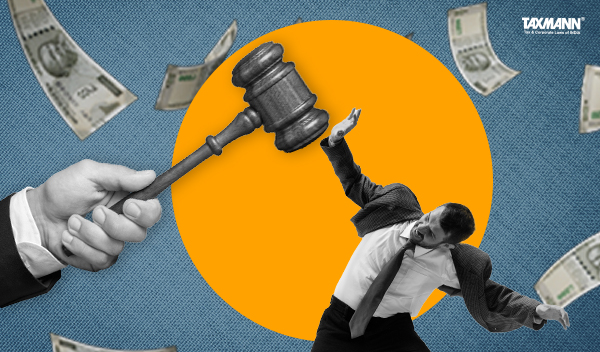
Tribunal Reduced Penalty Amount for FEMA Violations as Amount Imposed Was Excessive Compared to Contraventions
- News|Blog|FEMA & Banking|
- 2 Min Read
- By Taxmann
- |
- Last Updated on 24 May, 2024
Latest from Taxmann
Case Details: Shri Satpal Singh Vig @Pali v. Joint Director, Directorate of Enforcement - [2024] 162 taxmann.com 713 (SAFEMA - New Delhi)
Facts of the Case
In the instant case, Respondent received specific information that the appellant was receiving and accepting bets on scores and outcomes of cricket matches and other sporting events on behalf of their clients and bookies based locally, nationally and internationally and accordingly, a penalty was imposed by ED for alleged violation of section 3 and 4 of FEMA which had been assailed in the instant appeal.
It was noted that the respondent had not recorded a finding solely based on statements of the appellant and JS, who was said to be co-accused; however, it was also based on documents recovered from their business premises during search and seizure.
Further, JS’s statement was recorded in continuity from the date of search, 02.08.2004. His statement was recorded even on 03.08.2004, 8.09.2004, and 11.10.2004. He did not retract his statement immediately, so it could not be taken that statements were recorded with inducement.
The appellant’s position was similar. His statements were recorded on 03.08.2004, 04.08.2004, and 06.08.2004. Again, it was in continuity, and he did not raise any objection to recording his statement in four days by calling him. There was no retraction of his statement immediately thereupon.
Thus, the findings recorded by the respondent were error-free, and the penalty issue remains. A penalty of Rs. 26 lakhs was imposed for contravention of Section 4 and Rs. 98 lakhs for Section 3(d) of FEMA
ITAT Held
The Tribunal held that the penalty amount was in excess of contravention of the amount involved. The appellant had already deposited Rs.50 lakhs to satisfy the condition of pre-deposit.
Thus, to make the penalty amount proportionate to the contravention, it was to be reduced. Accordingly, for contravention of Section 4, a penalty of Rs.26 lakhs was to be reduced to Rs.10 lakhs. Similarly, a penalty of Rs.98 lakhs was to be reduced to Rs.40 lakhs. Accordingly, the appeal was partly allowed.
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.
Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com


 CA | CS | CMA


