Overview of Personal Guarantors Provisions under IBC
- Blog|Insolvency and Bankruptcy Code|
- 15 Min Read
- By Taxmann
- |
- Last Updated on 16 November, 2026
Latest from Taxmann

Table of Contents
- Framework For Personal Guarantors under IBC
- Jurisdiction of NCLT for Corporate Debtor, Corporate Guarantor and Personal Guarantor
- Insolvency Resolution Process
- Personal Guarantor
- Moratorium
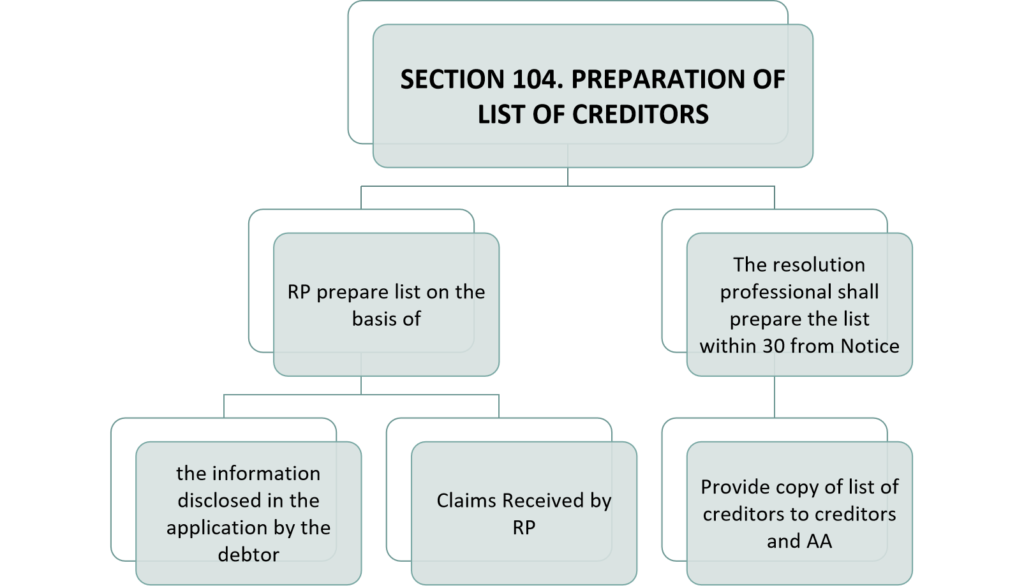
- Section 104 – Preparation of List of Creditors
- Repayment Plan (Section 105 And Reg. 17)
- Insolvency of Personal Guarantor Rules
- What changed in 2026?
- Quick answers
1. Framework For Personal Guarantors under IBC
In exercise of the powers conferred by sub-section (3) of Section 1 of the Insolvency and Bankruptcy Code, 2016 (31 of 2016), the Central Government hereby appoints the 1st day of December, 2019 as the date on which the following provisions of the said Code only in so far as they relate to personal guarantors to corporate debtors, shall come into force:
- clause (e) of section 2
- section 78 (except with regard to fresh start process) and section 79;
- sections 94 to 187 [both inclusive];
- clause (g) to clause (i) of sub-section (2) of section 239;
- clause (m) to clause (zc) of sub-section (2) of section 239;
- clause (zn) to clause (zs) of sub-section (2) of section 240; and
- section 249.
1.1 Framework
Insolvency Resolution Process
- Insolvency and Bankruptcy Board of India (Insolvency Resolution Process for Personal Guarantors to Corporate Debtors) Regulations, 2019.
- Insolvency and Bankruptcy (Application to Adjudicating Authority for Insolvency Resolution Process for Personal Guarantors to Corporate Debtors) Rules, 2019.
Bankruptcy Process
- Insolvency and Bankruptcy Board of India (Bankruptcy Process for Personal Guarantors to Corporate Debtors) Regulations, 2019.
- Insolvency and Bankruptcy (Application to Adjudicating Authority for Bankruptcy Processfor Personal Guarantors to Corporate Debtors) Rules, 2019.
1.2 Timeline
- 28.05.2016 – IBC enacted
- 15.11.2019 – Sections of the Code for Personal Guarantor notified
- 15.11.2019 – Rules for Personal Guarantor notified
- 20.11.2019 – Regulations for Personal Guarantor notified
- 01.12.2019 – Provisions along with Rules and Regulations For PG Insolvency Effective
2. Jurisdiction of NCLT for Corporate Debtor, Corporate Guarantor and Personal Guarantor
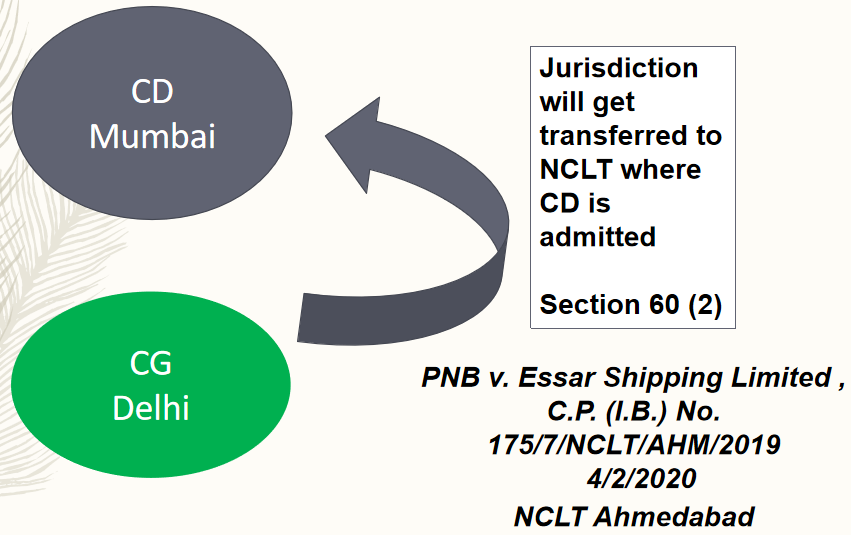
Two applications can be maintained for the same debt against CG and CD
Dr. Vishnu Kumar Agarwal v. Piramal Enterprises Ltd. [2019] 101 taxmann.com 464/151 SCL 555 (NCLAT) & Shabad Khan v. Nisus Finance and Investment Manager [2020] 118 taxmann.com 315 (NCLAT)
If two Applications can be filed, for the same amount against Principal Borrower and Guarantor keeping in view the Sec. 60(2) & (3) of IBC, the Applications can also be maintained – State Bank of India v. Athena Energy Ventures Private Limited [2021] 123 taxmann.com 82/164 SCL 293 (NCLAT)
Whether a Bank/Financial Institution can institute or continue with proceedings against a Guarantor under the SARFAESI Act, when proceedings under the IBC have been initiated against the Principal Borrower & the same are pending adjudication –
Kiran Gupta v. State Bank of India [2020] 121 taxmann.com 23 (Delhi) & Industrial Investment Bank of India Ltd. v. Biswanath Jhunjhunwala [2011] 3 taxmann.com 77 (SC)
3. Insolvency Resolution Process
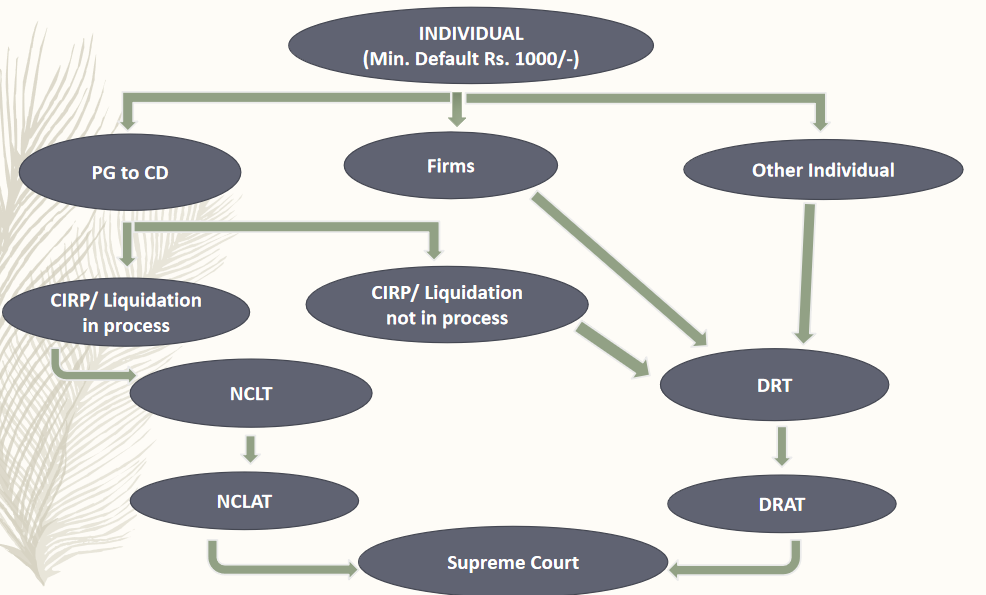
Note: the chart shows the earlier view that a personal guarantor’s case goes to the Debt Recovery Tribunal when the corporate debtor is not in CIRP or liquidation. In State Bank of India v. Mahendra Kumar Jajodia [2022] 136 taxmann.com 371 (NCL-AT), NCLAT held that the NCLT has jurisdiction under section 60(1) even then, and the Supreme Court declined to interfere.
3.1 Section 60 Adjudication Authority for Corporate Persons
- The Adjudicating Authority, in relation to insolvency resolution and liquidation for corporate persons including corporate debtors and personal guarantors thereof shall be the National Company Law Tribunal having territorial jurisdiction over the place where the registered office of a corporate person is located.
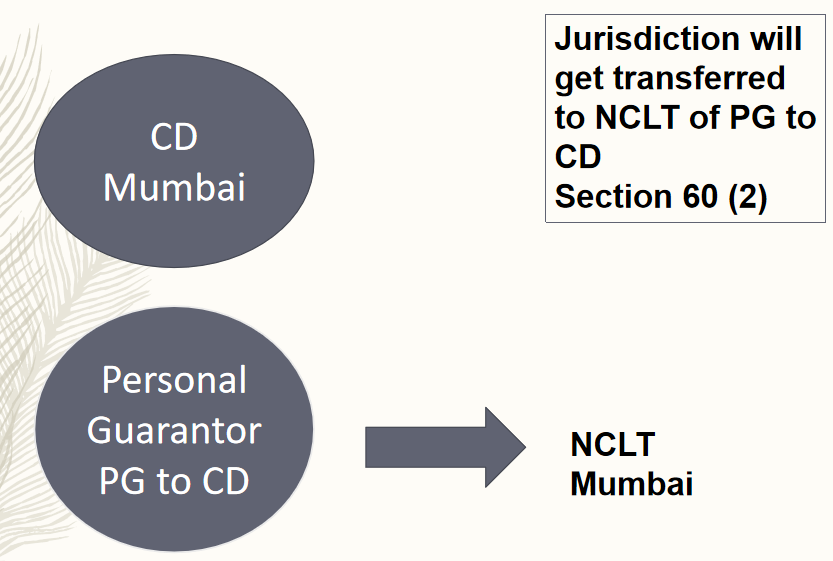
- Without prejudice to sub-section (1) and notwithstanding anything to the contrary contained in this Code, where a corporate insolvency resolution process or liquidation proceeding of a corporate debtor is pending before a National Company Law Tribunal, an application relating to the insolvency resolution or liquidation or bankruptcy of a corporate guarantor or personal guarantor, as the case may be, of such corporate debtor shall be filed before the National Company Law Tribunal.
- An insolvency resolution process or liquidation or bankruptcy proceeding of a corporate guarantor or personal guarantor, as the case may be, of the corporate debtor pending in any court or tribunal shall stand transferred to the Adjudicating Authority dealing with insolvency resolution process or liquidation proceeding of such corporate debtor.
- The National Company Law Tribunal shall be vested with all the powers of the Debt Recovery Tribunal as contemplated under Part III of this Code for the purpose of sub-section (2).
- Notwithstanding anything contained in the Limitation Act, 1963 or in any other law for the time being in force, in computing the period of limitation specified for any suit or application by or against a corporate debtor for which an order of moratorium has been made under this Part, the period during which such moratorium is in place shall be excluded.
- Notwithstanding anything to the contrary contained in any other law for the time being in force, the National Company Law Tribunal shall have jurisdiction to entertain or dispose of:
(a) any application or proceeding by or against the corporate debtor or corporate person;
(b) any claim made by or against the corporate debtor or corporate person, including claims by or against any of its subsidiaries situated in India; and
(c) any question of priorities or any question of law or facts, arising out of or in relation to the insolvency resolution or liquidation proceedings of the corporate debtor or corporate person under this Code.
3.2 Insolvency Resolution Process for Personal Guarantors
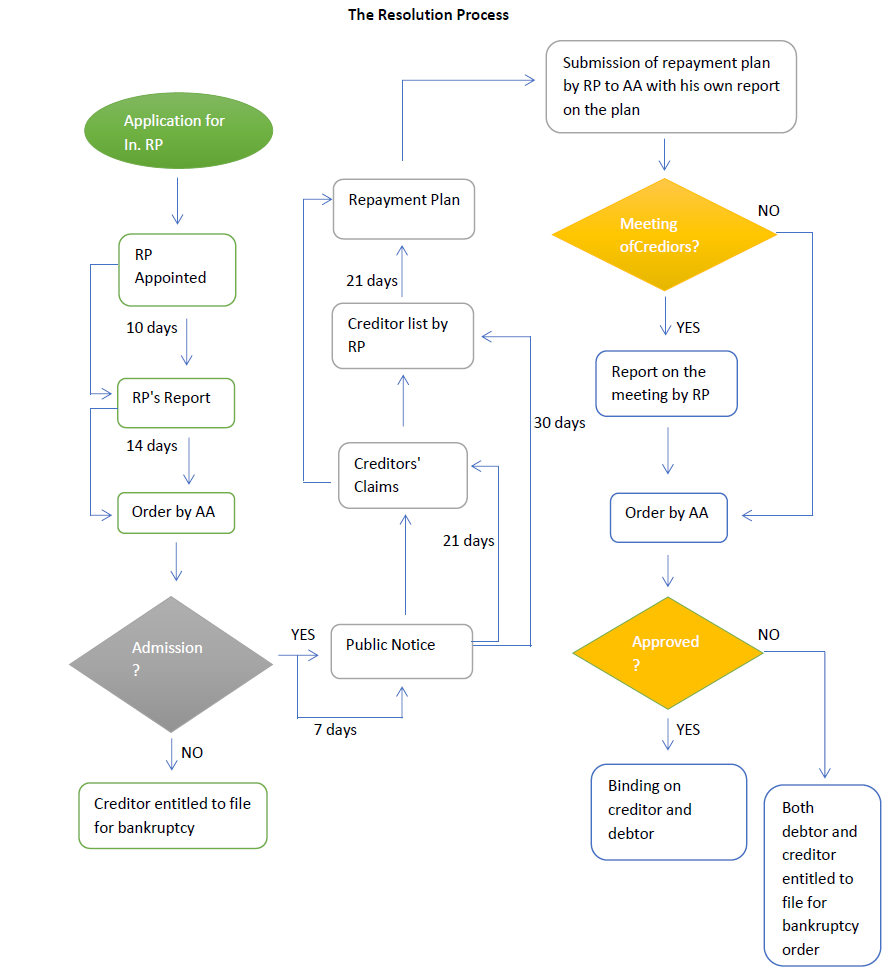
Note: this flowchart predates the 2026 amendments. The resolution professional now has 21 days, not 10, to report on the application (section 99(1)), and where the debtor is a personal guarantor to a corporate debtor the meeting of creditors is mandatory (section 106(3A)).
4. Personal Guarantor
- Section 5 (22)
- “personal guarantor” means an individual who is the surety in a contract of guarantee to a corporate debtor
- Rule 3 (f) of IBBI (Application to AA) Rules
- Guarantor means a debtor who is personal guarantor to a CD and in respect of whom guarantee has been invoked by the creditor and remain unpaid in full or part.
4.1 SC upholds Insolvency Resolution Process for Personal Guarantors
Lalit Kumar Jain vs Union of India [2021] 127 taxmann.com 368/167 SCL 1 (SC)
- Surety and Principal liability are co-extensive
- Contract of surety and variation in terms with principal
- Resolution plan of CD
4.2 Insolvency Resolution Process for Personal Guarantors
Application for Insolvency Resolution Process for personal guarantor-
- by guarantor personally or through RP (Form A u/s 94) along-with two thousand rupees.
- By Creditor (Section 95)
-
- Demand notice by creditor personally demanding payment [Form B]
14 days
-
- Application by creditor personally or through RP (Form C u/s 95) along-with two thousand rupees after expiry of 14 days from the date of demand notice.
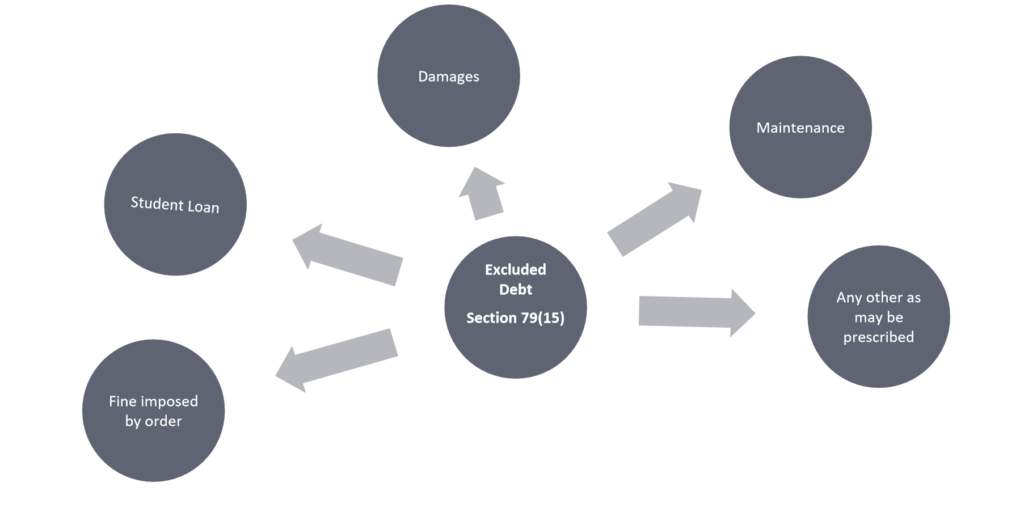
(15) “excluded debt” means
(a) liability to pay fine imposed by a court or tribunal;
(b) liability to pay damages for negligence, nuisance or breach of a statutory, contractual or other legal obligation;
(c) liability to pay maintenance to any person under any law for the time being in force;
(d) liability in relation to a student loan; and
(e) any other debt as may be prescribed;
Debtors not Able to File Application Section 94 (4)
- If debtor is an undischarged bankrupt
- undergoing a fresh start process
- undergoing an insolvency resolution process
- undergoing a bankruptcy process
5. Moratorium
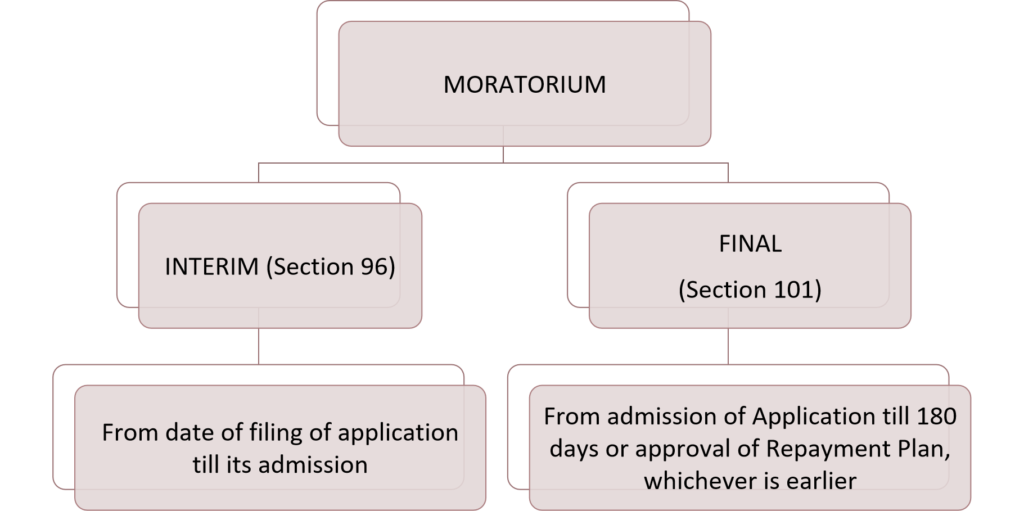
5.1 Interim Moratorium (Section 96)
During the interim-moratorium period –
- any pending legal action or proceeding in respect of any debt shall be deemed to have been stayed; and
- the creditors of the debtor shall not initiate any legal action or proceedings in respect of any debt.
Change from 26 May 2026: section 96(4) says the section does not apply where an application is filed for an insolvency resolution process of a personal guarantor to a corporate debtor. Filing under section 94 or 95 therefore no longer stays actions against such a guarantor. In Tata Capital Financial Services Ltd. v. Neel Motors LLP, 2026 LLBiz HC(BOM) 430, the Bombay High Court held that the change applies to applications already pending when it took effect. Even before 2026, the interim moratorium operated in respect of the debt, not the debtor (Dilip B. Jiwrajka v. Union of India [2023] 156 taxmann.com 304 (SC)), and it did not protect the principal borrower or other co-guarantors.
5.2 Final Moratorium (Section 101)
During the moratorium period-
- any pending legal action or proceeding in respect of any debt shall be deemed to have been stayed;
- the creditors shall not initiate any legal action or legal proceedings in respect of any debt; and
- the debtor shall not transfer, alienate, encumber or dispose of any of the assets or his legal right or beneficial interest therein;
P. Mohanraj v. Shah Brothers Ispat (P.) Ltd. [2021] 125 taxmann.com 39/167 SCL 327 (SC)
Supreme Court held that the benefit of Section 14 shall apply to Corporate Debtor and not to the “natural persons”
In a way, no benefit to extend on directors/signatory
Vicarious liability
Strict Liability
6. Section 104 – Preparation of List of Creditors
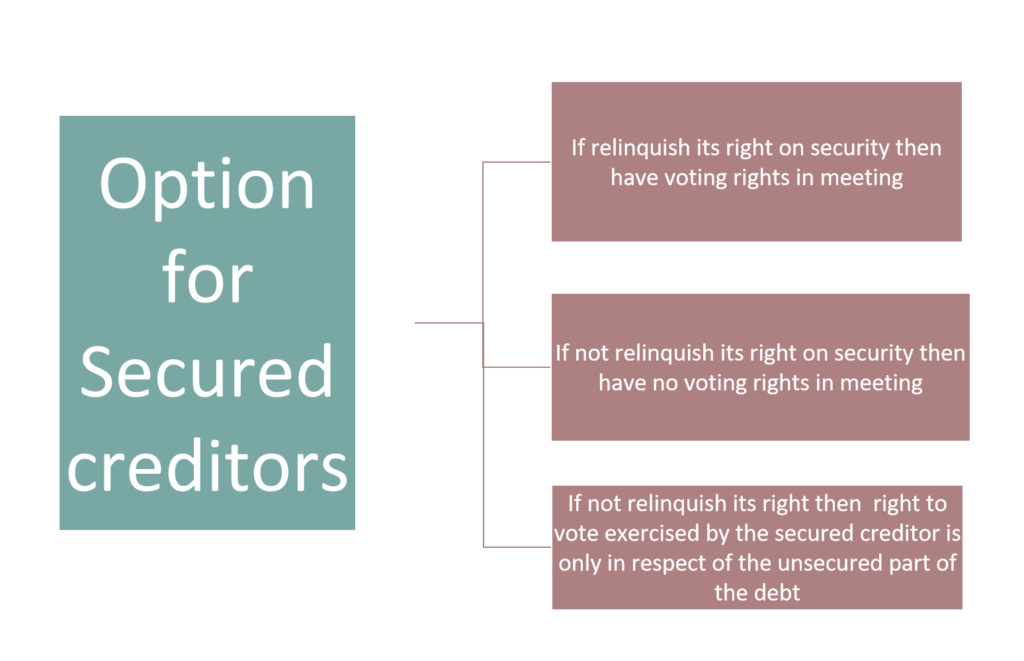
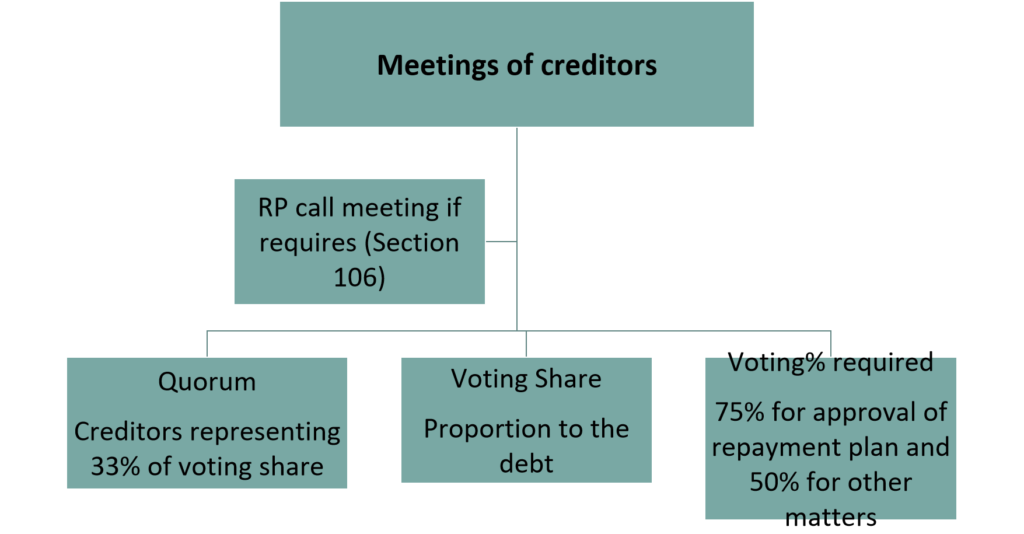
Note: since 26 May 2026, the meeting is mandatory where the debtor is a personal guarantor to a corporate debtor (section 106(3A)).
7. Repayment Plan (Section 105 And Reg. 17)
Section 105 (3)
(3) The repayment plan shall include the following, namely: –
(a) justification for preparation of such repayment plan and reasons on the basis of which the creditors may agree upon the plan;
(b) provision for payment of fee to the resolution professional;
(c) such other matters as may be specified.
Reg.17. Contents of repayment plan.
(1) The repayment plan shall provide the following –
(a) the term of the repayment plan and its implementation schedule, including the amounts to be repaid and dates of repayment to creditors;
(b) the source of funds that will be used to pay resolution process costs and that such payment shall be made in priority over any creditor;
(c) a minimum budget for the duration of the repayment plan, to cover the reasonable expenses of the guarantor and members of his immediate family to the extent they are dependent on him, provided that at least ten percent of the realisable income of the guarantor shall be utilised for repayment of debts;
(d) financing required for implementation of the repayment plan;
(e) if the guarantor has any business, the manner in which it is proposed to be conducted during the course of the repayment plan, and the role of the resolution professional;
(f) the manner in which funds held for the purposes of the repayment plan, invested or otherwise dealt with, pending repayment to creditors;
(g) the functions which are to be undertaken by the resolution professional, including supervision and implementation of the repayment plan;
(h) variation of onerous terms of a contract or transaction involving the guarantor;
(i) the details of excluded assets and excluded debts of the guarantor; and
(j) terms and conditions for the discharge of the guarantor.
(2) The repayment plan may provide for the following-
(a) transfer or sale of all or part of the assets of the guarantor along with the mode and manner of such sale;
(b) administration or disposal of any funds of the guarantor;
(c) satisfaction or modification of any security interest;
(d) reduction in the amount payable to creditors;
(e) curing or waiving of any breach of a debt due from the guarantor;
(f) modification in the terms of repayment of any debt due from the guarantor;
(g) part of the income of the guarantor to be used for the repayment of the debt, and the manner of calculating the income of the guarantor;
(h) the manner in which funds held for the purpose of repayment to creditors, and not so repaid at the end of the repayment plan, are to be dealt with; and
(i) such other matters as may be required by the creditors.
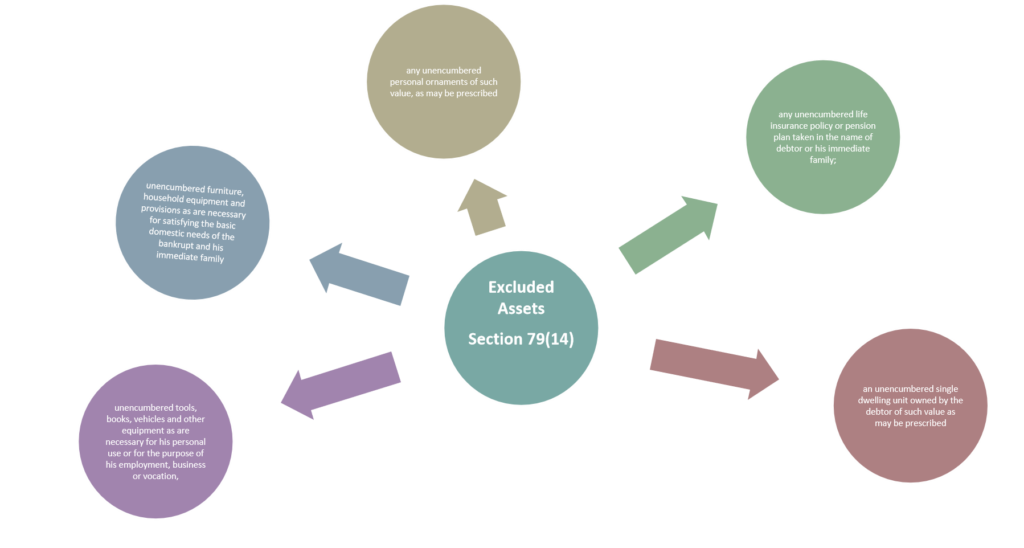
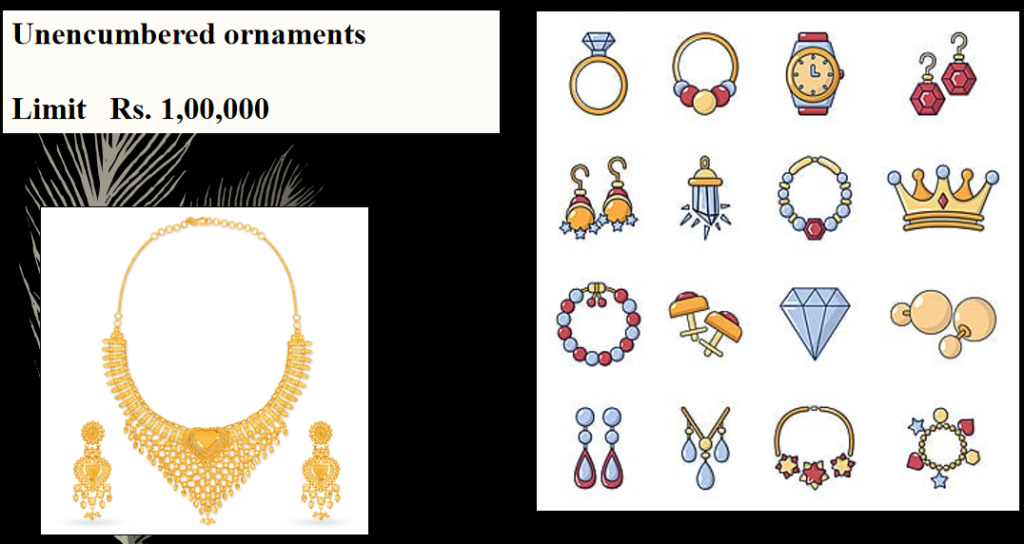
7.1 Excluded Assets – Section 79(14)
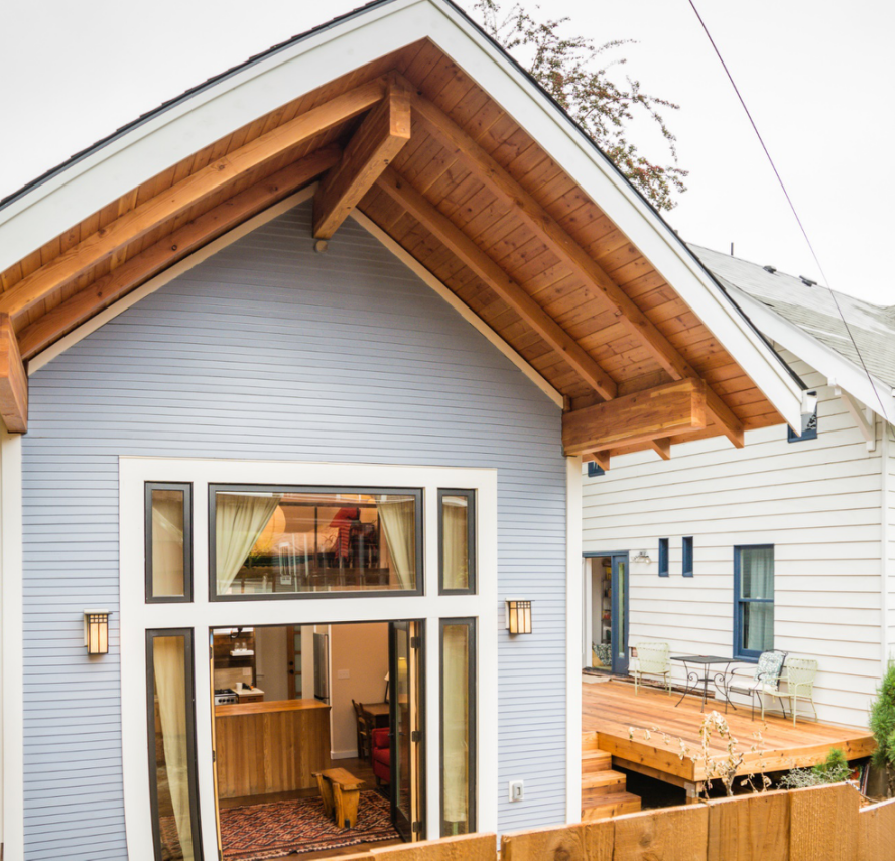
Unencumbered Single dwelling unit
10 lakhs – Rural
20 lakhs – Urban
7.2 Person prohibited to purchase assets (Reg. 18)
- the resolution professional or any partner or director of the insolvency professional entity of which the resolution professional is a partner or director
- any professional appointed by the resolution professional for the resolution process
- any creditor
- any company where the guarantor or a creditor is a promoter or director
- any associate of the guarantor, creditor or resolution professional
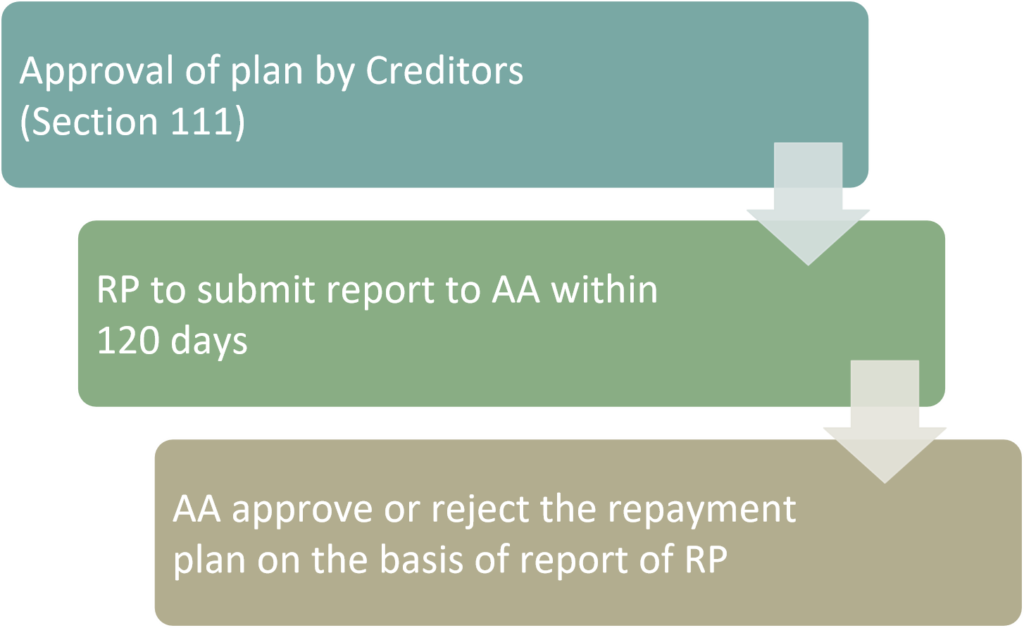
7.3 Report of RP on repayment plan (Section 106)
The report shall include that-
(a) the repayment plan is in compliance with the provisions of any law for the time being in force;
(b) the repayment plan has a reasonable prospect of being approved and implemented; and
(c) there is a necessity of summoning a meeting of the creditors, if required, to consider the repayment plan:
Provided that where the resolution professional recommends that a meeting of the creditors is NOT required to be summoned, reasons for the same shall be provided.
Since 26 May 2026, where the debtor is a personal guarantor to a corporate debtor, the resolution professional must summon the meeting of creditors by a written notice of its date, time and place (section 106(3A)). The meeting must be held 14 to 28 days after the report is submitted (section 106(4)). If no repayment plan is submitted within 21 days of the last date for claims, the resolution professional reports this, the NCLT terminates the process, and the debtor or the creditors may apply for bankruptcy (section 106(1A)).
7.4 Report of meeting of creditors on repayment plan (Section 112)
The report under sub-section (1) shall contain –
(a) whether the repayment plan was approved or rejected and if approved, the list the modifications, if any;
(b) the resolutions which were proposed at the meeting and the decision on such resolutions;
(c) list of the creditors who were present or represented at the meeting, and the voting records of each creditor for all meetings of the creditors; and
(d) such other information as the resolution professional thinks appropriate to make known to the Adjudicating Authority.
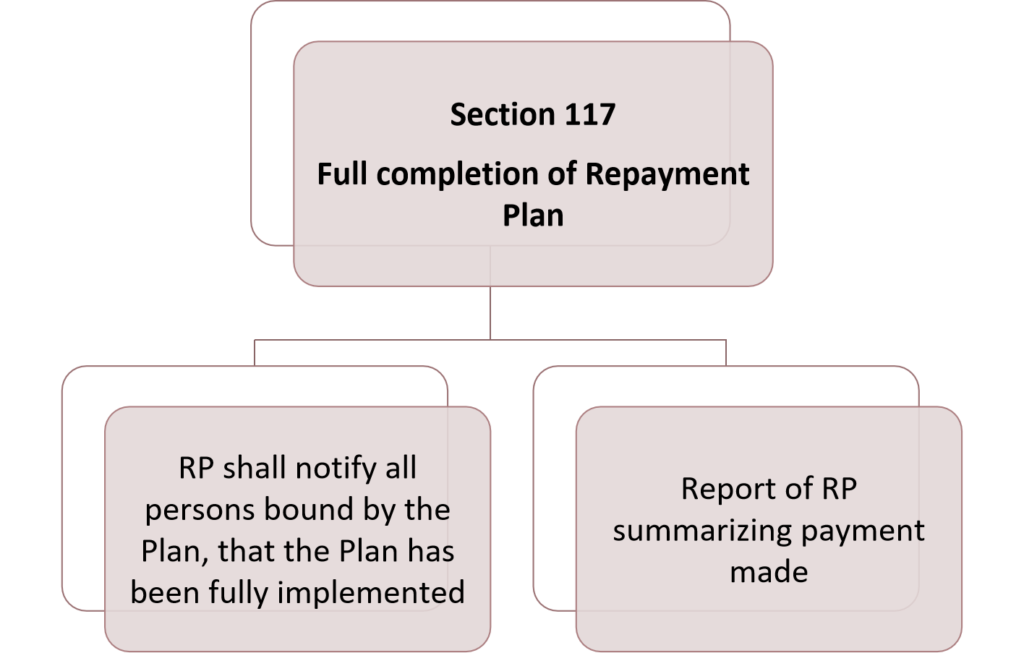
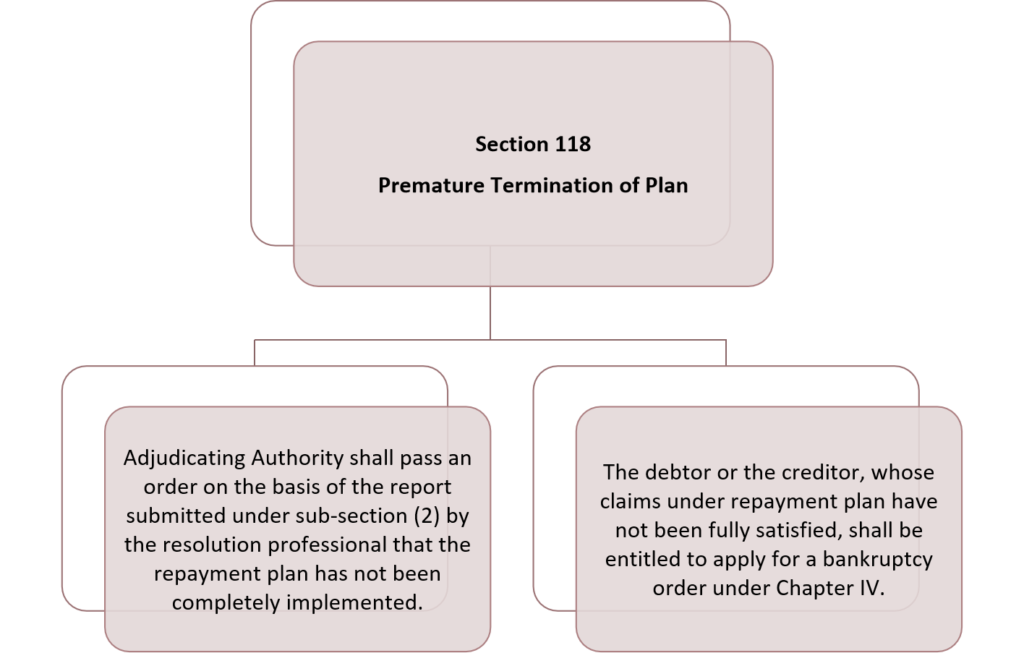 7.5 Discharge Order – (Section 119)
- On the basis of the repayment plan, the resolution professional shall apply to the Adjudicating Authority for a discharge order in relation to the debts mentioned in the repayment plan and the Adjudicating Authority may pass such discharge order.
- The repayment plan may provide for –
(a) early discharge; or
(b) discharge on complete implementation of the repayment plan
- The discharge order shall be forwarded to the Board, for the purpose of recording entries in the register referred to in section 196.
- The discharge order under sub-section (3) shall not discharge any other person from any liability in respect of his debt.
8. Insolvency of Personal Guarantor Rules
8.1 Who is Guarantor under Rules
As per Rule 3(e) of the rule “guarantor” means a debtor who is a personal guarantor to a corporate debtor and in respect of whom guarantee has been invoked by the creditor and remains unpaid in full or part;
Application to Adjudicating Authority under these rules can be filed By Two Persons;
- Application by Guarantors
- Application by Creditor
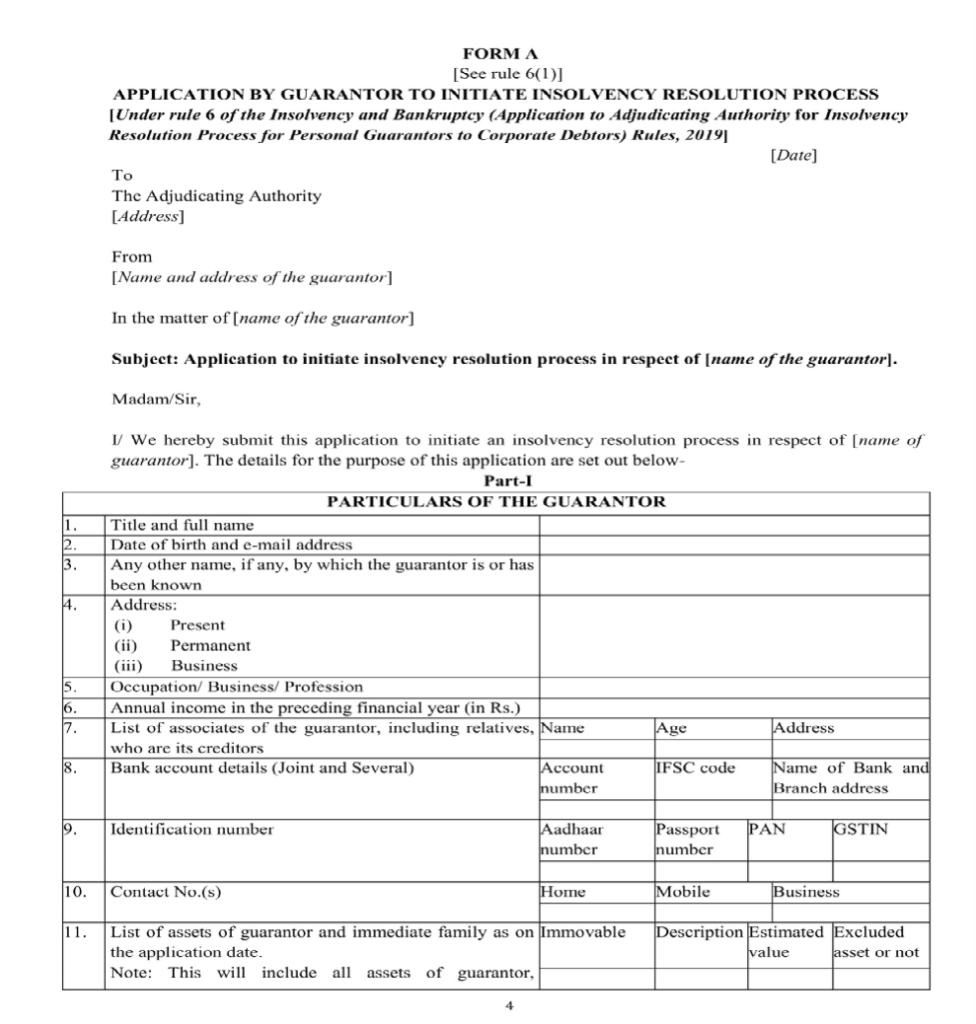
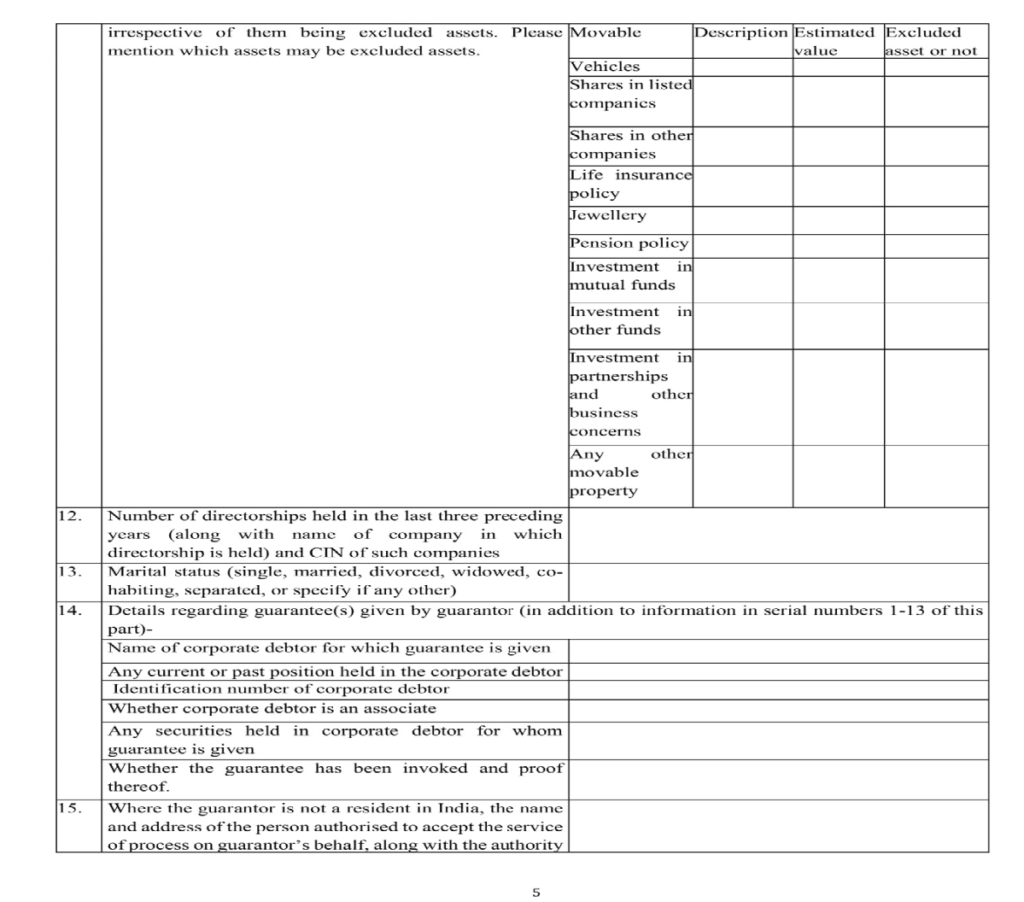
8.2 Application by Guarantor
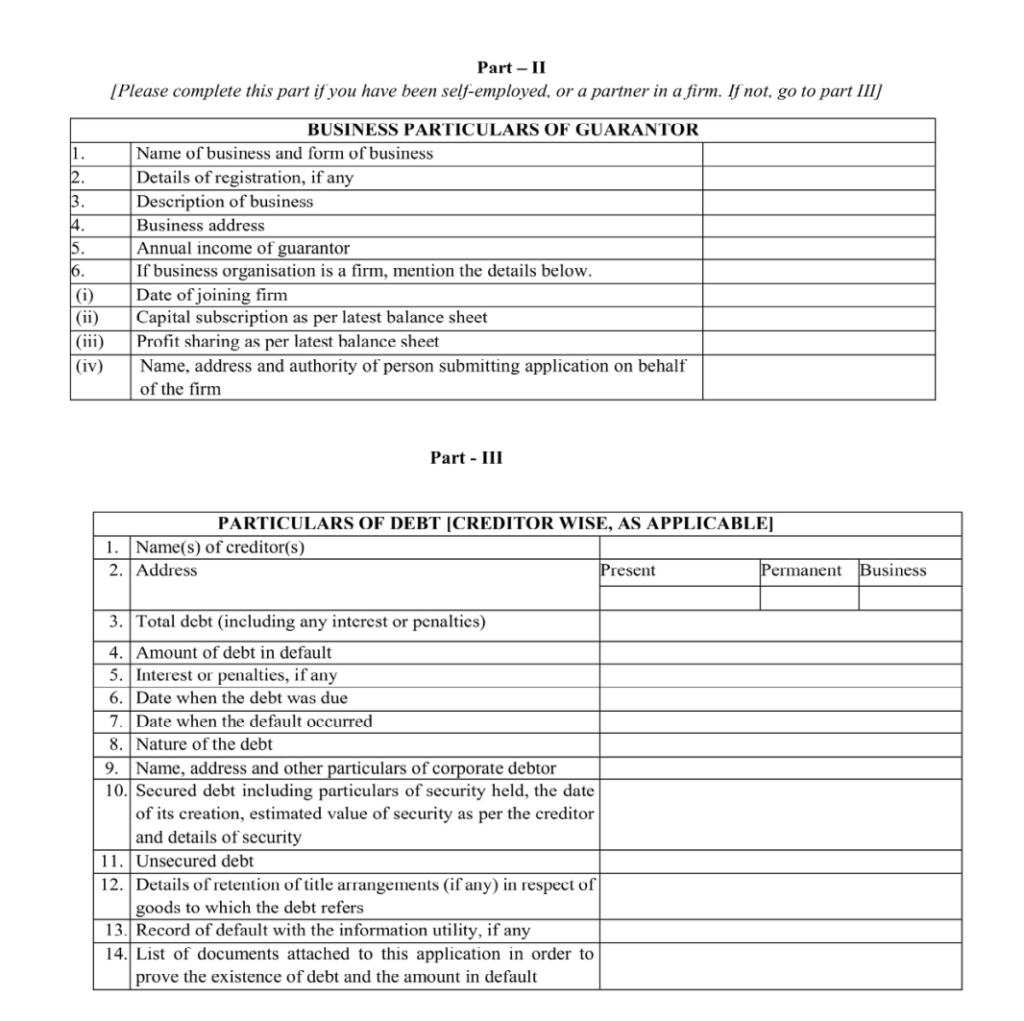
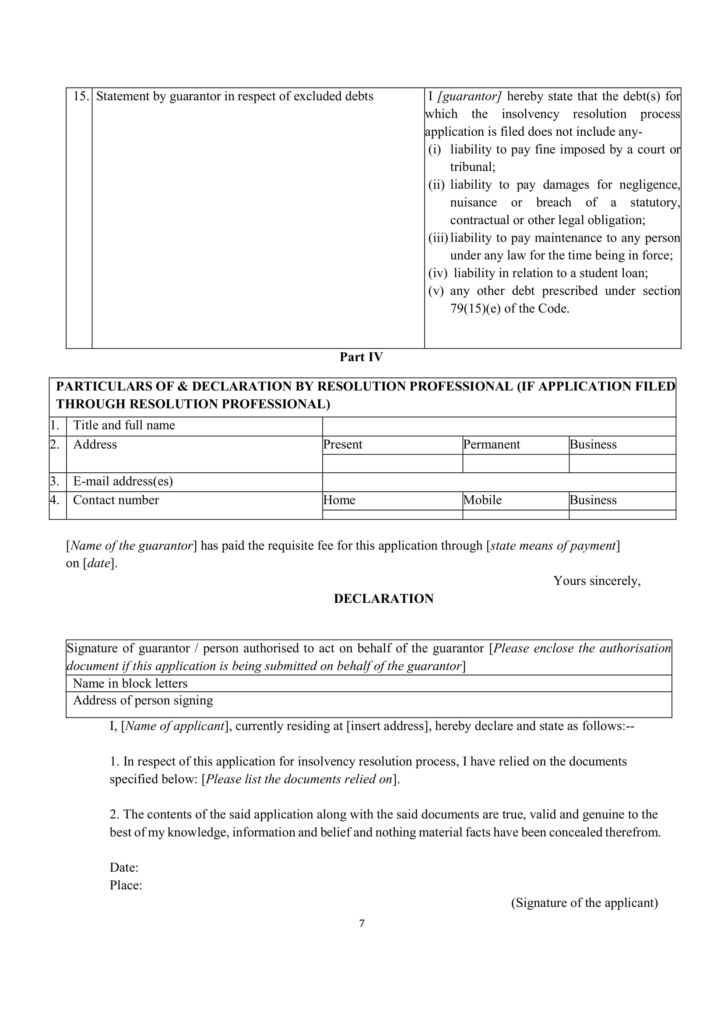
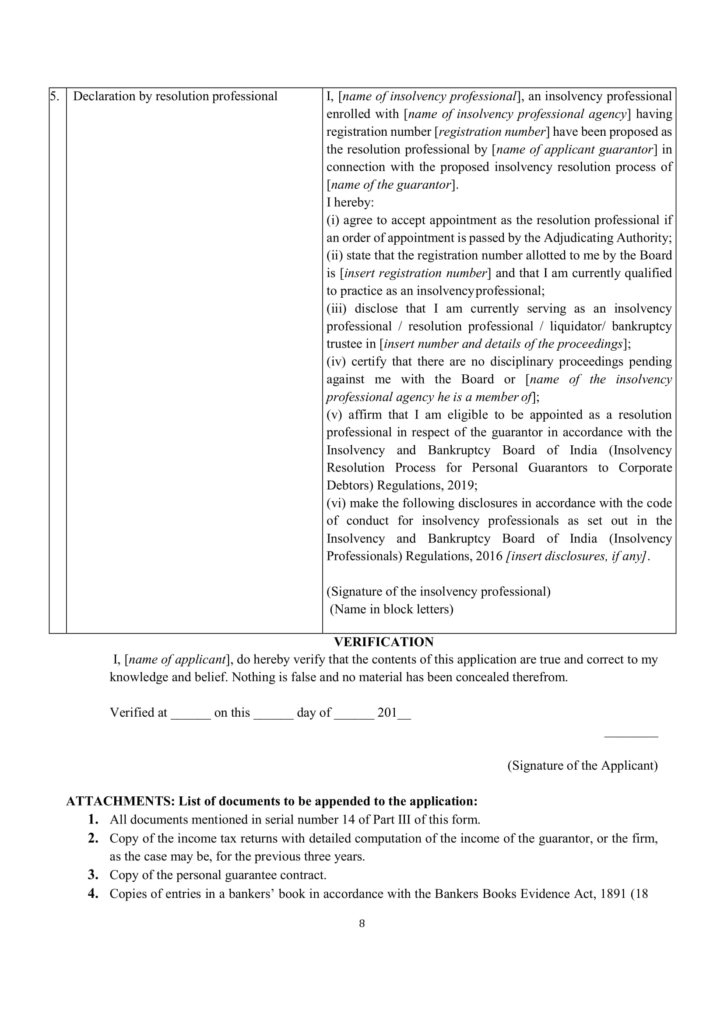
- An application under section 94(1) shall be submitted in Form A, along with an application fee of two thousand rupees.
- A copy of the application must be served on every financial creditor, on the corporate debtor for whom the guarantor is a personal guarantor and, if not provided earlier, on the resolution professional within three days of his appointment.
8.3 Application by Creditor
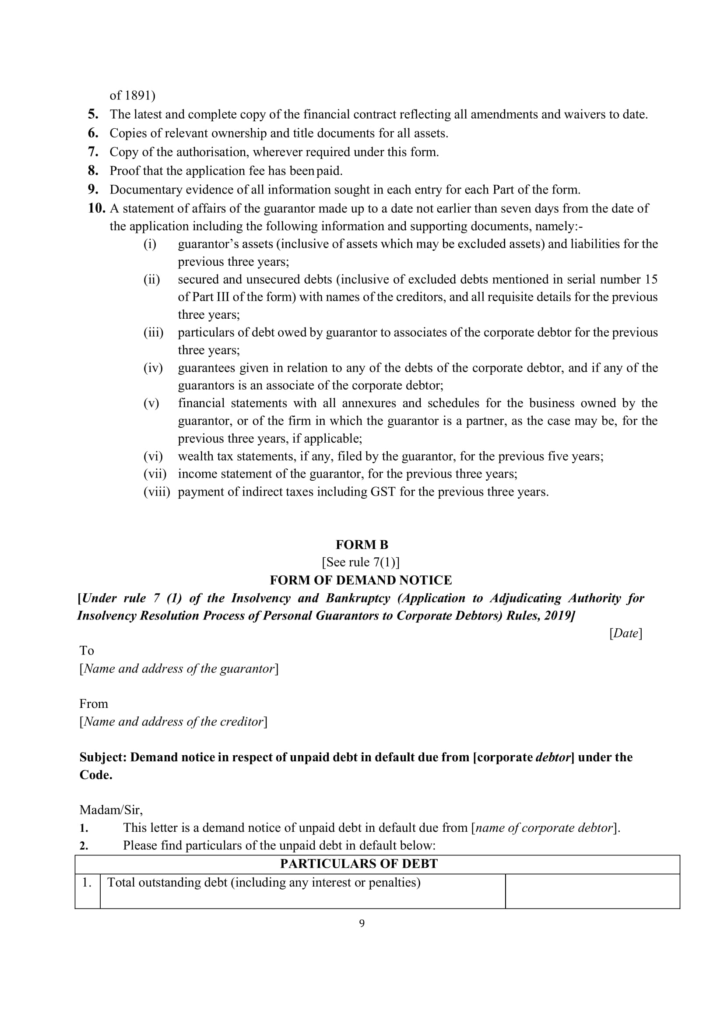
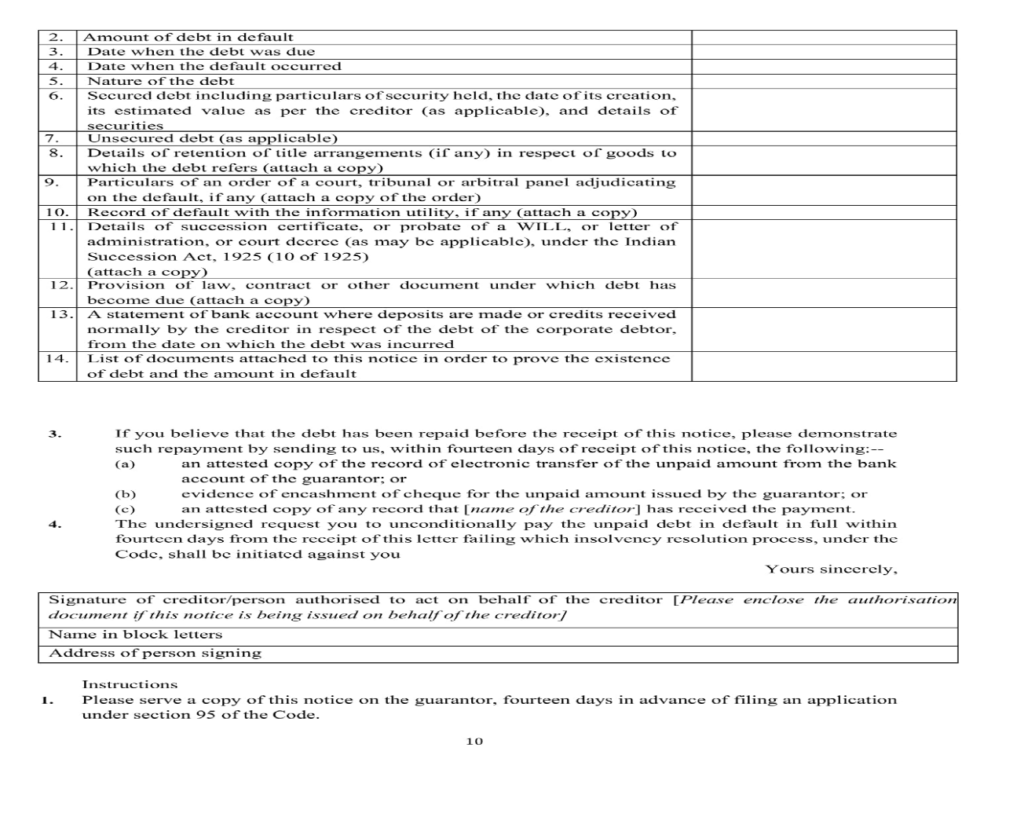
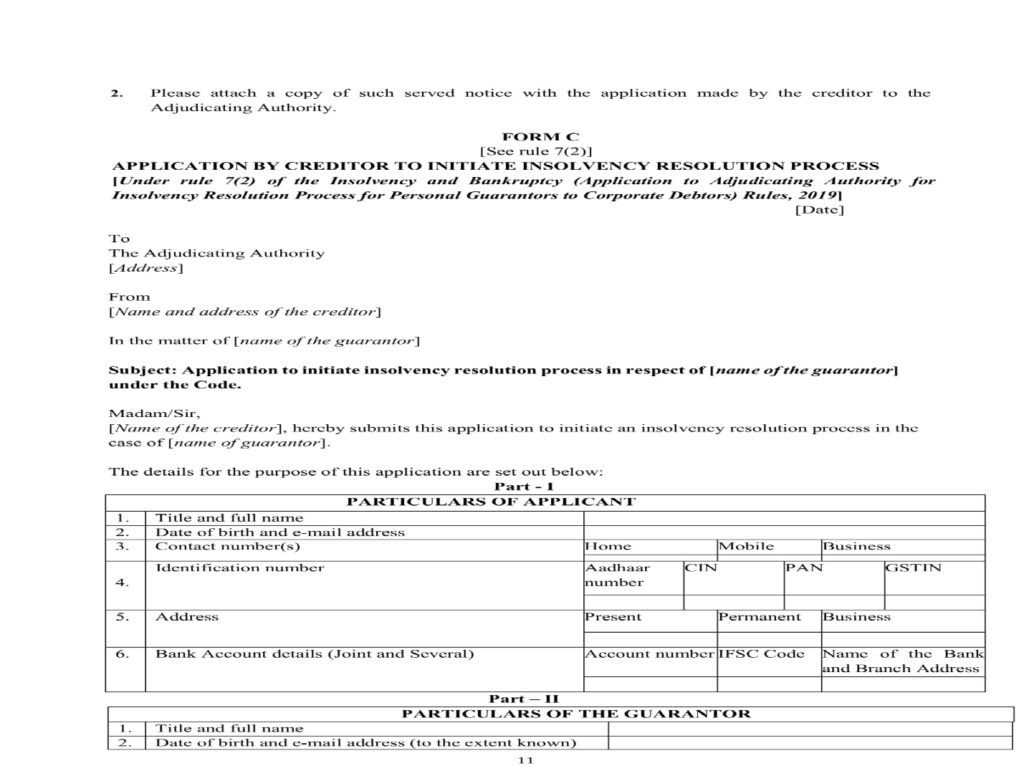
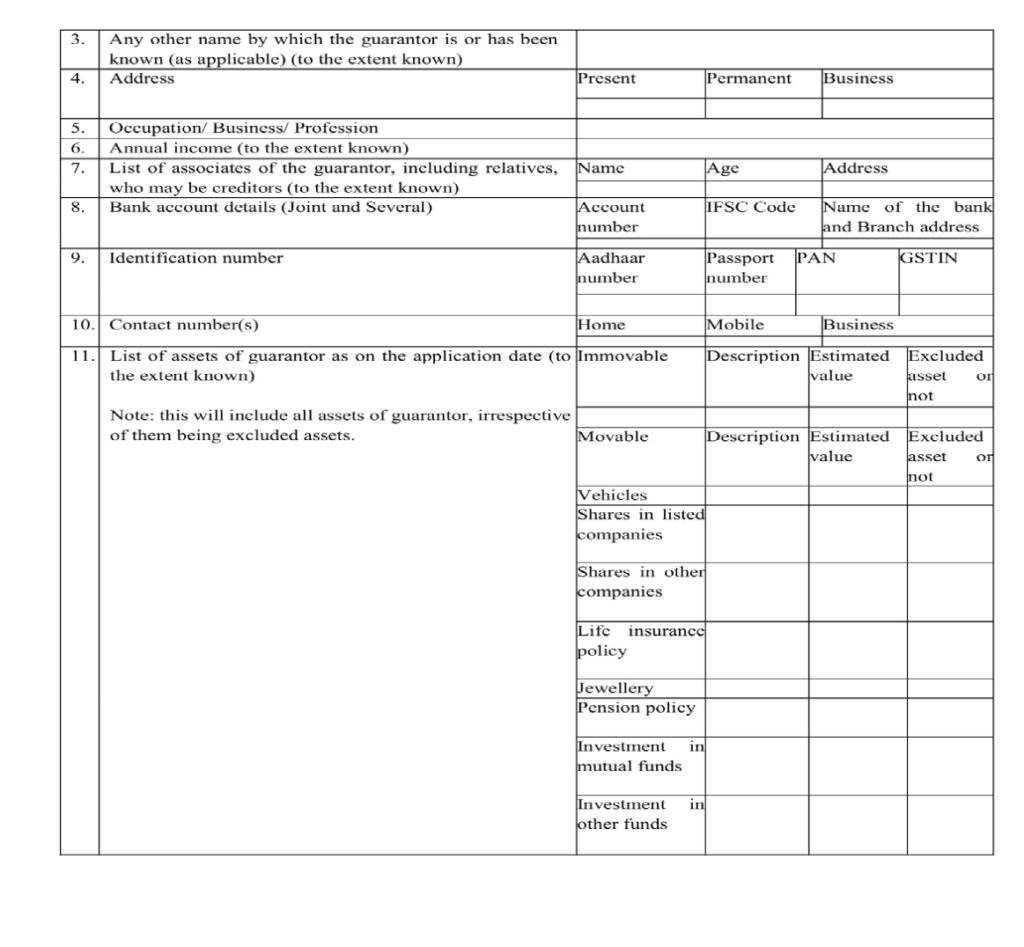
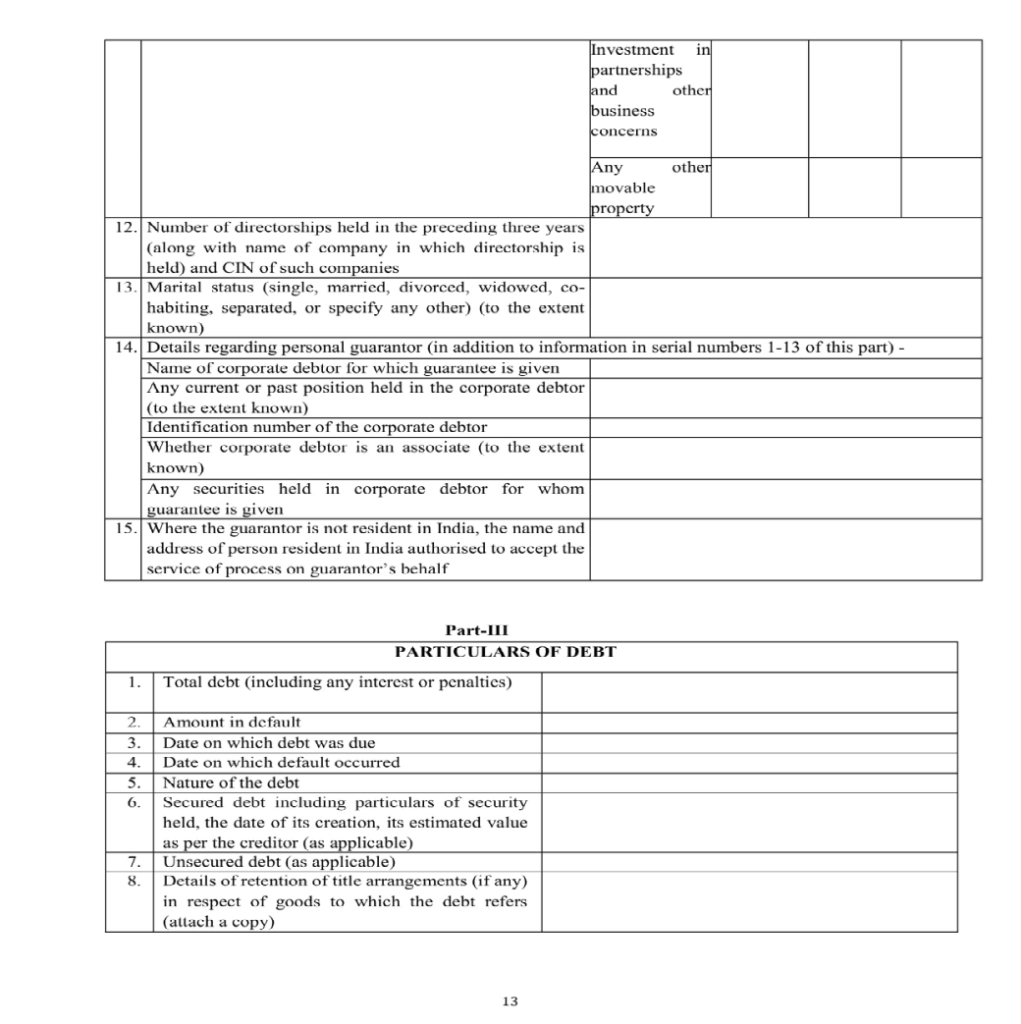
- The application under sub-section (1) of section 95 shall be submitted in Form C, along with a fee of two thousand rupees.
- A demand notice under clause (b) of sub-section (4) of section 95 shall be served on the guarantor demanding payment of the amount of default, in Form B.
- The copy of application must be served to the guarantor and the corporate debtor for whom the guarantor is a personal guarantor.
- In case of a joint application, the creditors may nominate one amongst themselves to act on behalf of all the creditors.
8.4 Confirmation or nomination of Insolvency Professional
- As per sec. 97(2) and 98(5) board may share the database of the insolvency professionals, including information about disciplinary proceedings against them, with the Adjudicating Authority from time to time.
- As per sec. 97(4) and 98 (3) the Board may share a panel of insolvency professionals, who may be appointed as resolution professionals, with the Adjudicating Authority.
8.5 Service of Petition to Resolution Professional
Applicant shall provide copy of application to the resolution professional if not provided earlier within three days of his appointment under sec. 97(5), and to the Board for its record.
8.6 Filing of Application and Documents
As there are no specific rules exist for Adjudicating Authority the applications under rules 6 and 7 shall be filed and dealt with by the Adjudicating Authority in accordance with:
- Rules 20, 21, 22, 23, 24 and 26 of Part III of the National Company Law Tribunal Rules, 2016 made under section 469 of the Companies Act, 2013 (18 of 2013); or
- Rule 3 of the Debt Recovery Tribunal (Procedure) Rules, 1993 made under section 36 of the Recovery of Debts and Bankruptcy Act, 1993 (51 of 1993) and regulations 3, 4, 5 and 11 of the Debt Recovery Tribunal Regulations, 2015 made under section 22 of the Recovery of Debts and Bankruptcy Act, 1993
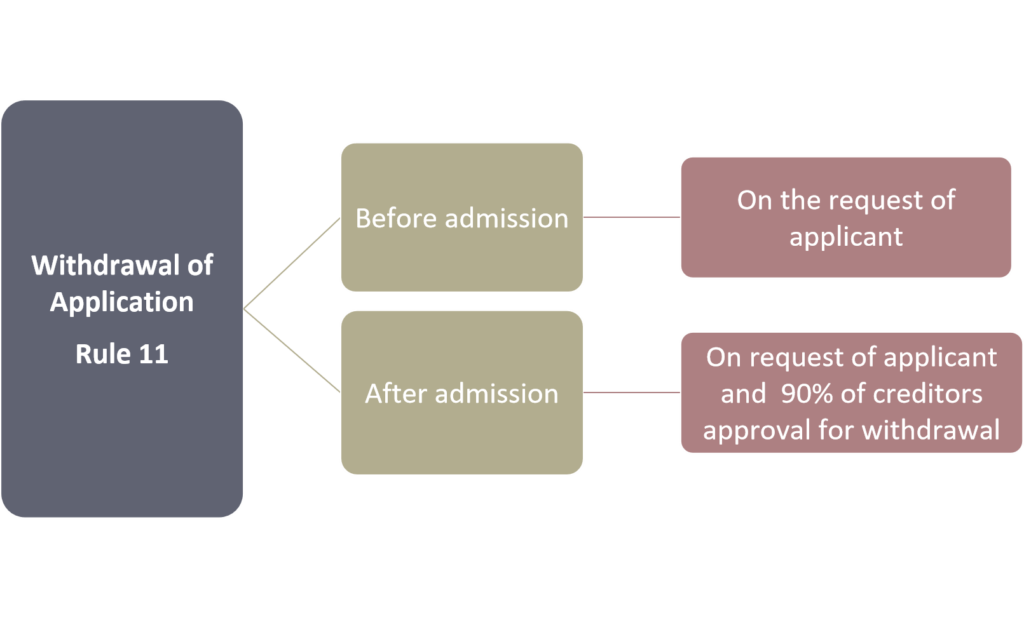
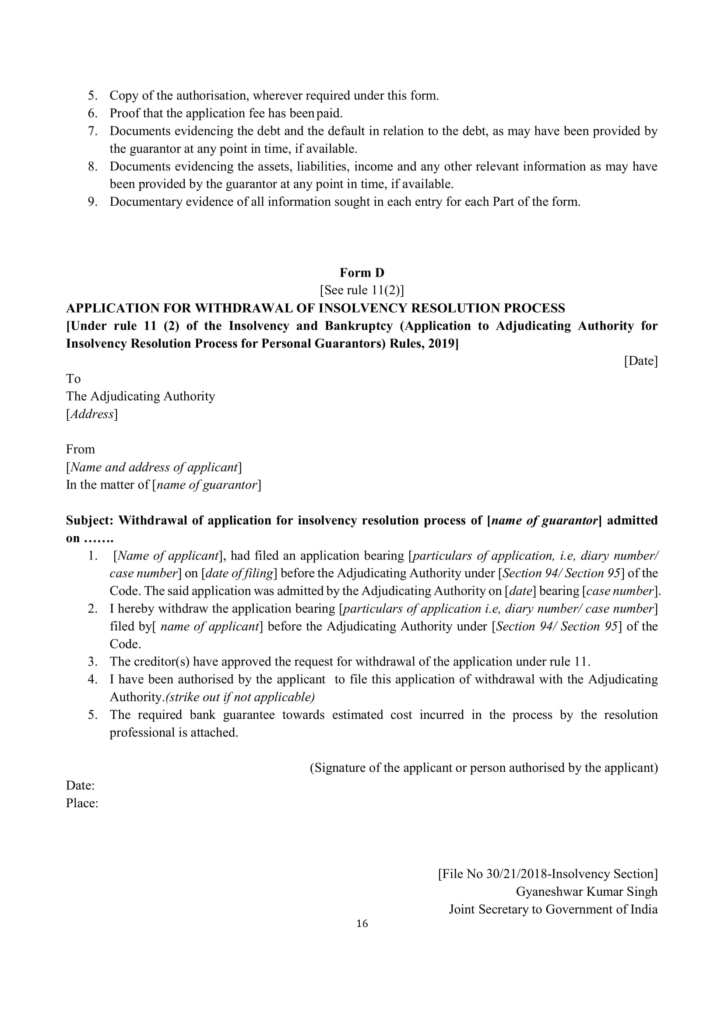
8.7 Withdrawal of Application
- The Adjudicating Authority may permit withdrawal of the application submitted under rule 6 or rule 7, as the case may be,-
(a) before its admission, on a request made by the applicant;
(b) after its admission, on the request made by the applicant, if ninety per cent of the creditors agree to such withdrawal.
- An application for withdrawal under clause (b) of sub-rule (1) shall be in Form D.
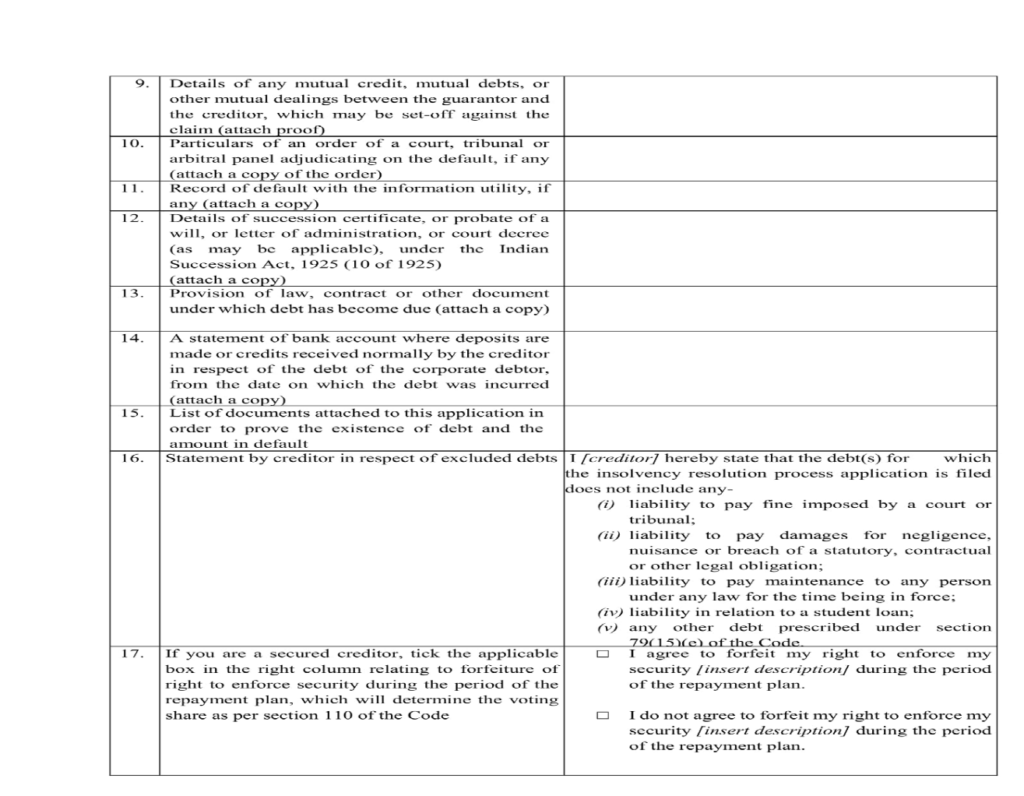
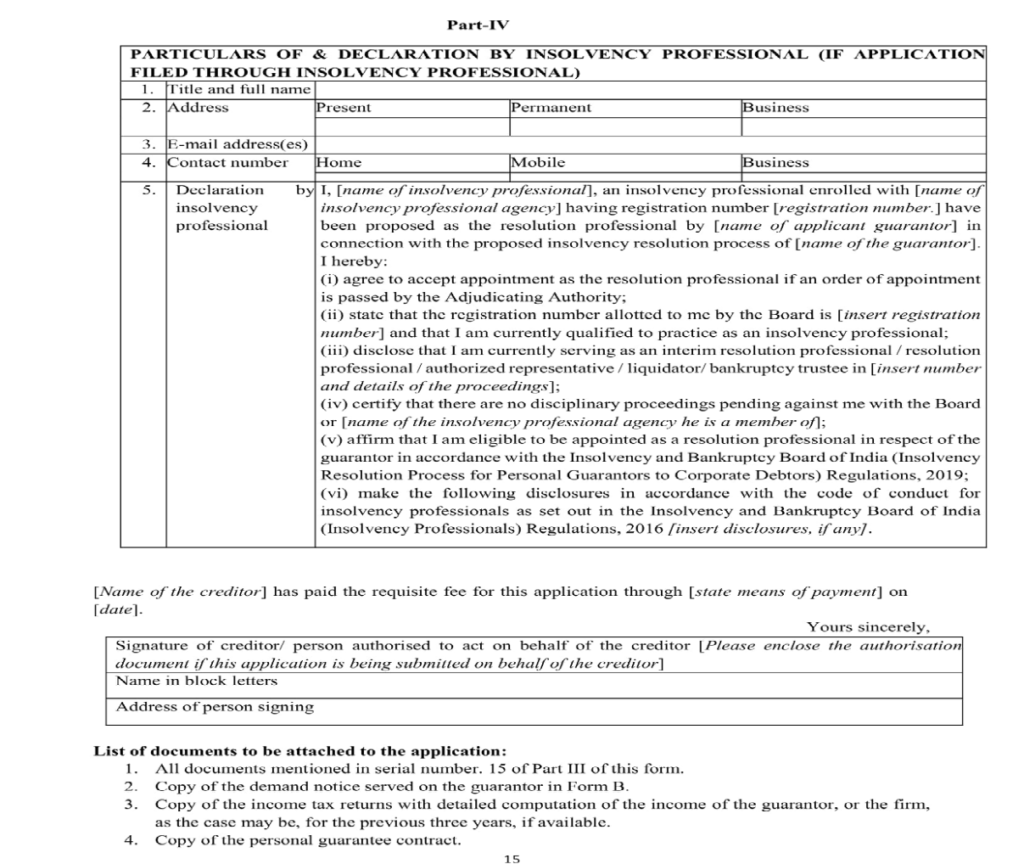
8.8 Various Forms Under Rules
9. What changed in 2026?
The Insolvency and Bankruptcy Code (Amendment) Act, 2026 changed the process for personal guarantors to corporate debtors with effect from 26 May 2026:
| Stage | Change from 26 May 2026 | Provision |
|---|---|---|
| Interim moratorium on filing | No longer applies to an application for the insolvency resolution process of a personal guarantor to a corporate debtor | Section 96(4) |
| Resolution professional’s report on the application | Within 21 days of appointment, instead of 10; a copy goes to both the debtor and the creditor | Section 99(1) and (10) |
| No repayment plan submitted in time | The NCLT terminates the process on the resolution professional’s report, and the debtor or the creditors may apply for bankruptcy | Section 106(1A) |
| Meeting of creditors | Mandatory where the debtor is a personal guarantor to a corporate debtor, held 14 to 28 days after the report | Section 106(3A) and (4) |
A 2026 amendment to the IBBI (Insolvency Resolution Process for Personal Guarantors to Corporate Debtors) Regulations, 2019 also requires a complete and true statement of all assets, with supporting evidence, to be filed with an application under section 94 or 95.
Two points did not change. The moratorium under section 101 still starts when the NCLT admits the application and lasts up to 180 days or until the order on the repayment plan, whichever is earlier. And in State Bank of India v. V. Ramakrishnan [2018] 96 taxmann.com 271 (SC), the Supreme Court held that the section 14 moratorium in the corporate debtor’s CIRP does not extend to its personal guarantors. Our note on the moratorium under section 14 covers that side, and our analysis of the IBC (Amendment) Act 2026 covers the other changes.
10. Quick answers
Who is a personal guarantor under IBC?
An individual who is the surety in a contract of guarantee to a corporate debtor (section 5(22)). The insolvency Rules for personal guarantors apply once the creditor has invoked the guarantee and it remains unpaid in full or in part.
Who can apply under section 95 of IBC?
A creditor, alone, jointly with other creditors or through a resolution professional. It must first invoke the guarantee, serve a demand notice in Form B and wait 14 days, and then apply in Form C. NCLAT has held that an application without prior invocation of the guarantee is not maintainable.
Does section 96 give a personal guarantor an interim moratorium?
Not since 26 May 2026. Section 96(4) excludes applications for the insolvency resolution process of a personal guarantor to a corporate debtor, and the Bombay High Court has applied this to applications already pending on that date. The moratorium under section 101 still starts once the NCLT admits the application.
Which tribunal hears insolvency cases against a personal guarantor?
The NCLT, even when no CIRP or liquidation of the corporate debtor is pending: section 60(1) names the bench with territorial jurisdiction over the corporate debtor’s registered office, as NCLAT held in State Bank of India v. Mahendra Kumar Jajodia. Where a CIRP or liquidation is pending, section 60(2) requires the application to be filed before that NCLT.
How long does the resolution professional have to report under section 99?
21 days from appointment, up from 10 days before 26 May 2026. The report recommends whether the NCLT should accept or reject the application, and a copy goes to both the debtor and the creditor.
Does a resolution plan for the corporate debtor discharge the personal guarantor?
No. In Lalit Kumar Jain v. Union of India [2021] 127 taxmann.com 368 (SC), the Supreme Court held that approval of a resolution plan does not by itself discharge a personal guarantor’s liability under the contract of guarantee.
The 2026 changes above draw on the commentary on sections 94 to 106 in Taxmann’s Law Relating to Insolvency & Bankruptcy by Vinod Kothari and Sikha Bansal (2nd Edition, two volumes): a section-wise commentary on the Insolvency and Bankruptcy Code, 2016 with a table comparing the section 96 interim moratorium with the section 14 moratorium, with the law stated as on 30th September 2026.
The text of the Code, the Rules and Regulations for personal guarantors and the rulings cited above are available in the Insolvency & Bankruptcy Code module of Taxmann.com Research.
Related reading: Moratorium under section 14 of IBC · CIRP under IBC · Section 29A of IBC · IBC (Amendment) Act 2026: key changes.
Disclaimer: The content/information published on the website is only for general information of the user and shall not be construed as legal advice. While the Taxmann has exercised reasonable efforts to ensure the veracity of information/content published, Taxmann shall be under no liability in any manner whatsoever for incorrect information, if any.

Taxmann Publications has a dedicated in-house Research & Editorial Team. This team consists of a team of Chartered Accountants, Company Secretaries, and Lawyers. This team works under the guidance and supervision of editor-in-chief Mr Rakesh Bhargava.
The Research and Editorial Team is responsible for developing reliable and accurate content for the readers. The team follows the six-sigma approach to achieve the benchmark of zero error in its publications and research platforms. The team ensures that the following publication guidelines are thoroughly followed while developing the content:
- The statutory material is obtained only from the authorized and reliable sources
- All the latest developments in the judicial and legislative fields are covered
- Prepare the analytical write-ups on current, controversial, and important issues to help the readers to understand the concept and its implications
- Every content published by Taxmann is complete, accurate and lucid
- All evidence-based statements are supported with proper reference to Section, Circular No., Notification No. or citations
- The golden rules of grammar, style and consistency are thoroughly followed
- Font and size that’s easy to read and remain consistent across all imprint and digital publications are applied
Everything on Tax and Corporate Laws of India
To subscribe to our weekly newsletter please log in/register on Taxmann.com









 CA | CS | CMA


